
A crash with an uninsured driver in Santa Cruz can leave you confused about what happens next. You might wonder if your insurance covers the damage, or whether you have any legal options to recover costs.
We at Schaar & Silva LLP help accident victims navigate these situations every day. This guide walks you through your rights, the steps to take immediately after the accident, and how to protect yourself moving forward.
Who Are Uninsured Motorists and Why Santa Cruz Drivers Should Care
Understanding Uninsured and Underinsured Drivers
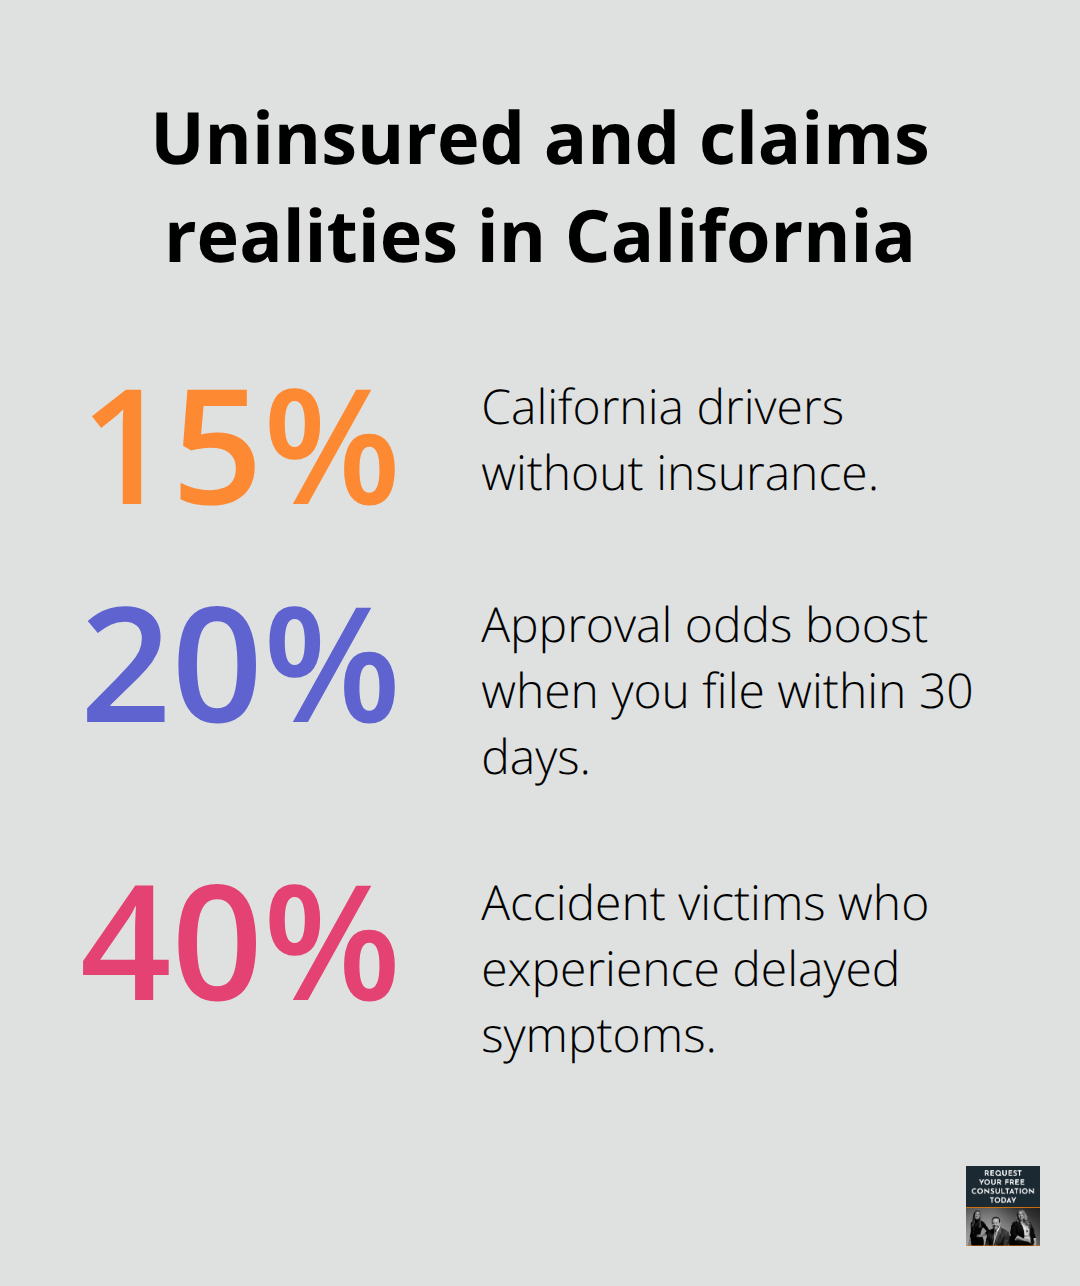
An uninsured motorist is someone driving without active auto insurance coverage. In California, this is illegal, yet it remains remarkably common. The Insurance Research Council reports that about 15% of California drivers operate without insurance, meaning roughly one in every seven vehicles on Santa Cruz roads lacks coverage. When you’re hit by an uninsured driver, your own insurance becomes your lifeline because the at-fault driver cannot pay for your medical bills, lost wages, or vehicle repairs.
Underinsured motorists present a similar problem: they carry insurance, but their policy limits fall short of covering the full damage they cause. If an underinsured driver causes $75,000 in injuries but carries only $15,000 in liability coverage, that $60,000 gap becomes your problem unless you have underinsured motorist protection.
Why Santa Cruz Drivers Face Real Risks
California law requires insurers to offer uninsured motorist coverage, though you can decline it in writing. Declining this coverage is a serious mistake in Santa Cruz County, where local data shows real collision risks. In 2021 alone, Santa Cruz experienced 13 hit-and-run incidents and 49 bicycle-involved crashes, many involving uninsured drivers who fled the scene. These numbers reflect the tangible threat uninsured drivers pose to your financial security.
How Uninsured Motorist Coverage Protects You
Uninsured motorist coverage works by compensating you through your own insurance policy when an uninsured or hit-and-run driver causes an accident. The coverage pays your medical expenses, lost wages, pain and suffering, and vehicle repairs up to the limits you selected. If you chose uninsured motorist bodily injury coverage, it covers injury-related costs. Uninsured motorist property damage coverage typically covers up to around $3,500 in vehicle repairs.
The Claims Process and Timeline
Most insurers require you to carry uninsured motorist limits matching your liability limits for true protection, though many policies default to lower amounts. The process begins when you file a claim with your own insurer rather than pursuing the uninsured driver directly, which is far simpler when the driver is untraceable or has no assets to recover from.
Filing your claim within 30 days significantly improves approval chances by roughly 20%, according to insurance industry data. California’s two-year statute of limitations for personal injury claims means missing this window can permanently bar your recovery, making speed essential. The strength of your claim depends on documentation you gather at the scene: police reports, witness statements, photos of damage, and medical records.
What Happens When Claims Fall Short
Victims often lose thousands because they failed to gather evidence or notify their insurer promptly, not because their coverage was inadequate. The difference between a successful recovery and a denied claim frequently comes down to the actions you take in the first hours and days after the accident. Understanding what steps to take immediately after a crash with an uninsured driver can mean the difference between protecting your rights and losing them entirely.
How to Protect Your Rights After an Uninsured Motorist Accident
File Your Claim Promptly and Accurately
Contact your insurer within 24 hours and explicitly state that the other driver was uninsured. Provide your policy number, the date and time of the accident, the location, and your police report number. The California Department of Insurance reports that filing within 30 days improves approval odds by roughly 20%, so treat this as a hard deadline. Do not provide a recorded statement before consulting an attorney, as insurers sometimes use these statements to minimize payouts.
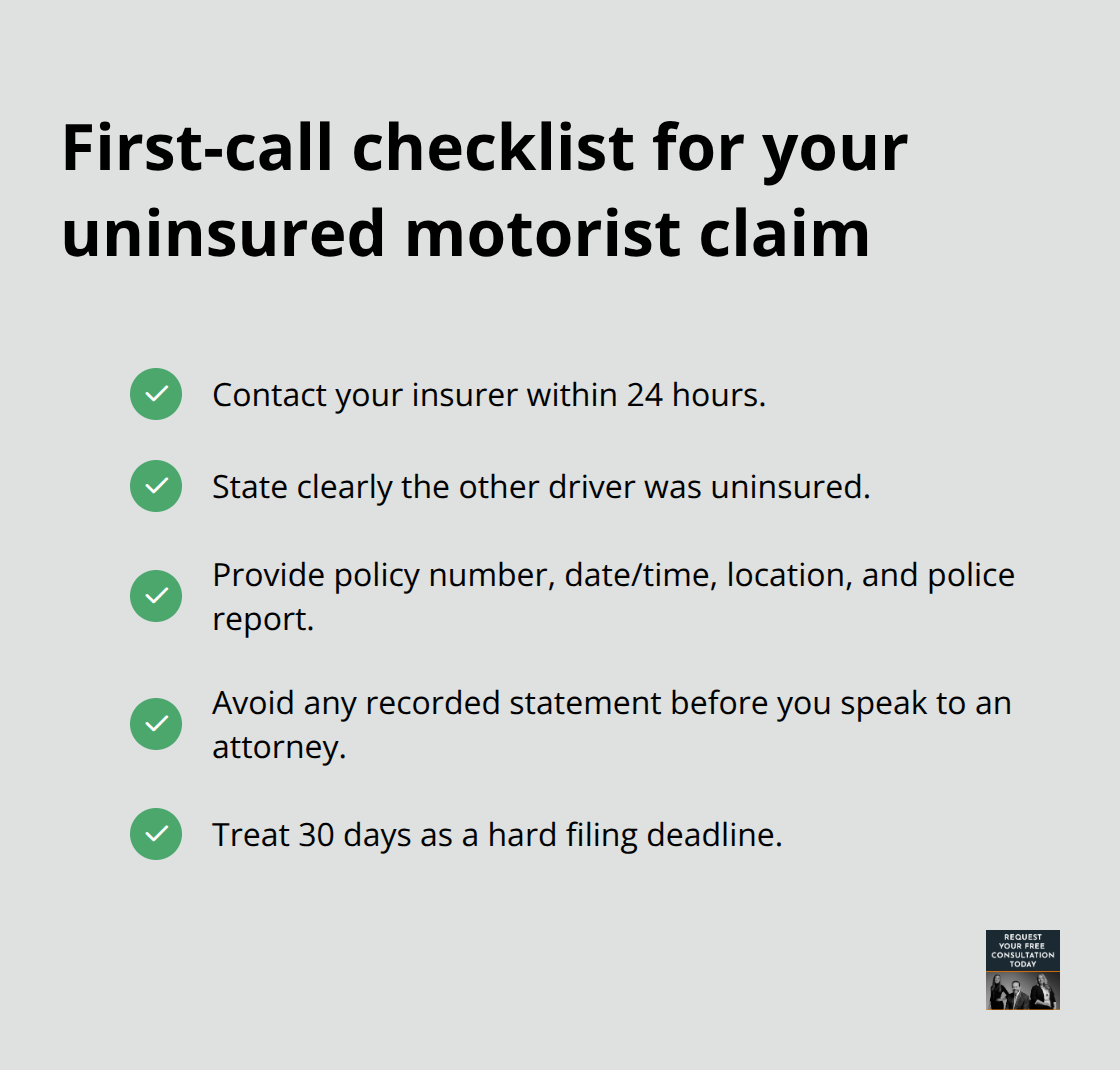
Speed and precision in this initial notification set the tone for your entire claim.
Understand Your Coverage Limits
Your uninsured motorist bodily injury coverage pays your medical expenses, lost wages, and pain and suffering up to your policy limits. Uninsured motorist property damage coverage typically covers up to around $3,500 in vehicle repairs. The critical mistake most Santa Cruz residents make is carrying limits far below their liability coverage. If your liability limit is $100,000 but your uninsured motorist limit sits at $15,000, you’ve created a massive protection gap. Match your uninsured motorist limits to your liability limits for genuine security.
Gather Evidence at the Scene
When the at-fault driver remains at the scene, document their name, license number, license plate, and vehicle identification number before leaving. Gather at least two independent witnesses and obtain their contact information. Take photos of vehicle damage and scene conditions. These actions form the foundation of your claim’s strength and prevent disputes later about what actually happened.
Build Your Medical Documentation
Seek medical care promptly even if you feel fine, as up to 40% of accident victims experience delayed symptoms that affect coverage eligibility. Document every medical visit, test, prescription, and expense. Track missed work days with pay stubs or employer statements. If medical bills become overwhelming, medical lien services can cover costs while your case resolves, allowing you to focus on recovery rather than financial stress.
Know When Legal Action Becomes Necessary
Pursuing a personal injury lawsuit against an uninsured driver is rarely worthwhile because most lack assets to satisfy a judgment. Instead, your own uninsured motorist coverage provides the practical path forward. California’s two-year statute of limitations for personal injury claims applies, but your policy’s arbitration deadline may be shorter and must be observed. If your insurer disputes fault, injury severity, or the uninsured status, you may need legal action to recover what you’re owed. When disputes arise over your claim, consulting with an attorney can help you navigate the process and protect your interests.
What to Do Right Now After an Uninsured Driver Hits You
The first hours after a collision with an uninsured driver determine whether you’ll recover your losses or watch them disappear. Your actions in those initial moments-before shock fades and memory becomes unreliable-create the evidence foundation for everything that follows.
Secure the Scene and Call for Help
Call 911 immediately if anyone is injured and request a police report number, which strengthens your claim significantly. While waiting for police, do not admit fault to anyone. Write down the other driver’s name, license number, license plate, and vehicle identification number if they remain at the scene. Take photos of all vehicle damage, the accident scene, traffic conditions, and any visible injuries. Gather at least two independent witnesses and obtain their full contact information, since witness statements often prove decisive when insurers or opposing parties dispute what happened.
Handle Hit-and-Run Situations
If the other driver flees, note their vehicle description, color, and any partial plate information you observed. These details matter because hit-and-run cases in Santa Cruz County-which averaged 13 incidents annually as of 2021-require solid documentation when the driver cannot be immediately identified. The police report becomes your primary evidence in these situations.
Notify Your Insurer Within 24 Hours
Contact your own insurance company within 24 hours and explicitly state that the other driver was uninsured. Provide your policy number, the exact date and time of the accident, the location, and your police report number. Do not provide a recorded statement before consulting an attorney, as insurers sometimes use these statements to minimize what they owe you. This initial notification sets the tone for your entire claim.
Seek Medical Care and Document Everything
Seek medical attention promptly even if you feel fine, because up to 40% of accident victims experience delayed symptoms that can affect your coverage eligibility and damage claims. Document every medical visit, test, prescription, and expense, and keep records of any missed work with pay stubs or employer statements. If medical bills pile up while your case resolves, medical lien services can cover those costs so you’re not trapped between recovery and financial collapse. This documentation becomes your evidence that injuries are real and damages are quantifiable, not speculation.
Build Your Claim Foundation
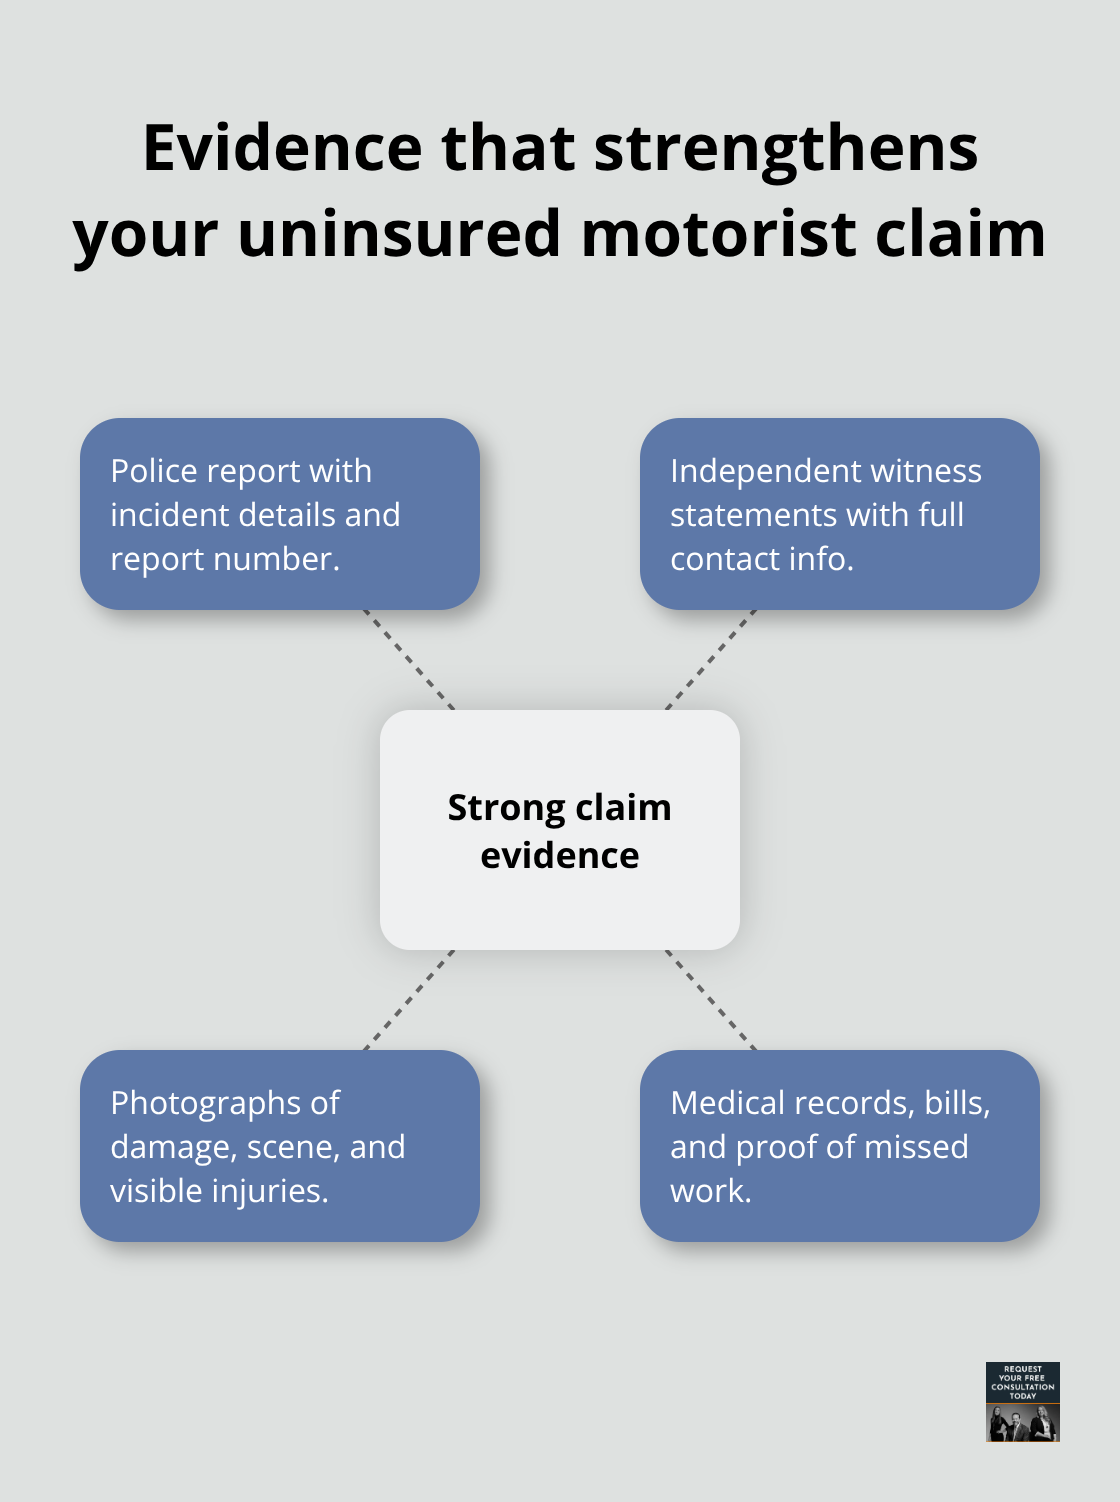
The strength of your claim depends entirely on what you gather in these first days, not on what you hope to remember later. Police reports, witness statements, photographs, and medical records form the foundation that determines your recovery. When disputes arise over liability or injury severity, this documentation proves invaluable in protecting your interests.
Final Thoughts
After an accident with an uninsured motorist in Santa Cruz, your recovery hinges on the decisions you make immediately. Review your current insurance policy and verify that your uninsured motorist limits match your liability coverage, since most Santa Cruz residents carry limits far below what they actually need. If your policy limits sit at $15,000 while your liability coverage reaches $100,000, you’ve left yourself vulnerable to significant losses that could have been prevented.
Settlement negotiations begin once your insurer completes its investigation and reviews your medical documentation. Insurers will evaluate your injuries, medical expenses, lost wages, and vehicle damage against your policy limits, and many victims accept the first offer without understanding what their claim is truly worth. If your insurer’s offer seems low or disputes your injuries, push back with additional medical evidence or witness statements, since the strength of your documentation directly influences the settlement amount you’ll receive.
We at Schaar & Silva LLP help Santa Cruz accident victims protect their rights when disputes arise with insurers or settlement negotiations stall. Contact us to discuss your uninsured motorist claim and learn how legal representation shifts the balance in your favor.
