A collision with an uninsured driver can leave you facing unexpected medical bills, vehicle repairs, and lost income. If this happened to you in Santa Cruz County, you’re not alone-thousands of drivers here face this situation every year.
Your uninsured motorist coverage exists specifically for these moments. We at Schaar & Silva LLP help Santa Cruz residents understand their options and recover the compensation they deserve.
How Many Uninsured Drivers Are on Santa Cruz Roads
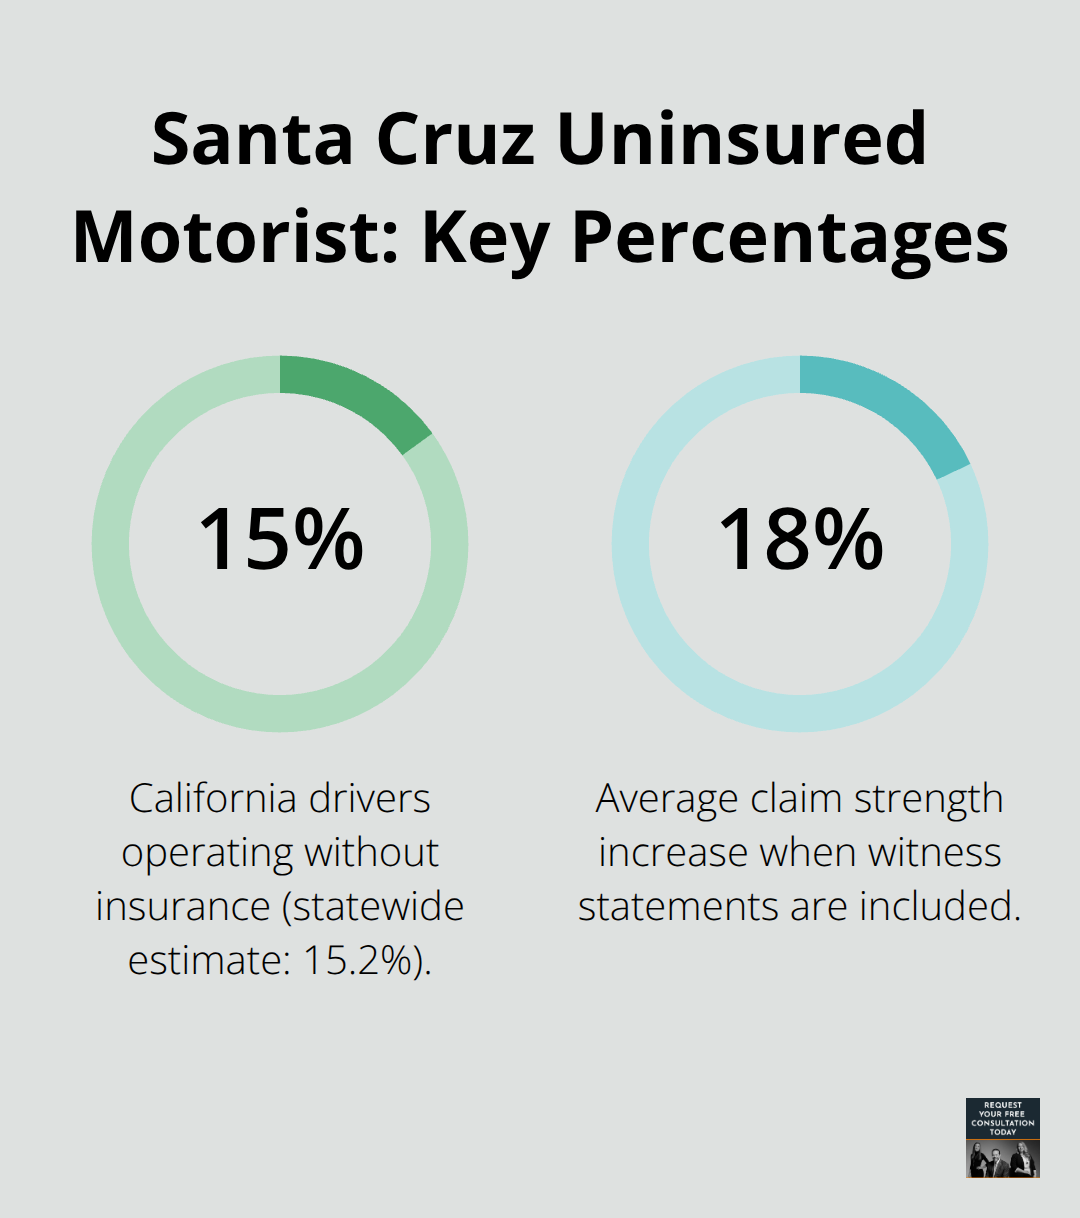
Uninsured drivers represent a genuine threat to your financial security in Santa Cruz County. According to the California Department of Insurance, approximately 15.2 percent of drivers statewide operate vehicles without insurance. That means roughly one in every seven vehicles you encounter on Highway 17 or local roads lacks coverage.
Santa Cruz County mirrors this statewide problem closely, with thousands of uninsured motorists creating risk for residents every single day. The Insurance Institute for Highway Safety reports that uninsured driver claims have risen consistently over the past five years, and Santa Cruz County has experienced this same upward trend. When an uninsured driver hits you here, the financial burden falls directly on your shoulders unless you carry uninsured motorist protection.
Why Drivers Skip Insurance in Santa Cruz
Drivers skip insurance for straightforward reasons: cost and risk calculation. California’s minimum liability insurance costs around 80 to 120 dollars monthly depending on age and driving record, and many Santa Cruz residents working in service industries or gig economy jobs view this as an unaffordable expense. Others operate vehicles temporarily, believing they’ll secure insurance next month. Some drivers simply underestimate the legal penalties, which include license suspension, vehicle impoundment, and fines exceeding 1,500 dollars for first-time violations.
Who Faces the Highest Risk
The problem intensifies among younger drivers aged 18 to 25, who represent a disproportionate share of uninsured motorists in the county. Low-income neighborhoods in Santa Cruz experience higher uninsured rates than affluent areas, reflecting broader economic disparities. This reality makes uninsured motorist coverage not optional but genuinely necessary for protecting yourself and your family.
What This Means for Your Protection
Understanding these statistics matters because they show you’re not dealing with a rare scenario. Thousands of Santa Cruz residents carry uninsured motorist coverage specifically because the risk here is real and measurable. Your next step involves understanding exactly what your coverage protects you against.
What Your Coverage Protects
Uninsured motorist coverage operates differently than standard liability insurance, and understanding these distinctions matters for your claim. Your policy covers medical bills stemming from the accident, including emergency room visits, hospital stays, surgery, physical therapy, and ongoing treatment. If the accident forced you to miss work, your uninsured motorist coverage reimburses lost wages up to your policy limits. California law permits recovery for pain and suffering damages as well, which compensates you for physical pain, emotional distress, and reduced quality of life resulting from your injuries. Property damage coverage under uninsured motorist protection pays for vehicle repairs or replacement value if your car is totaled.
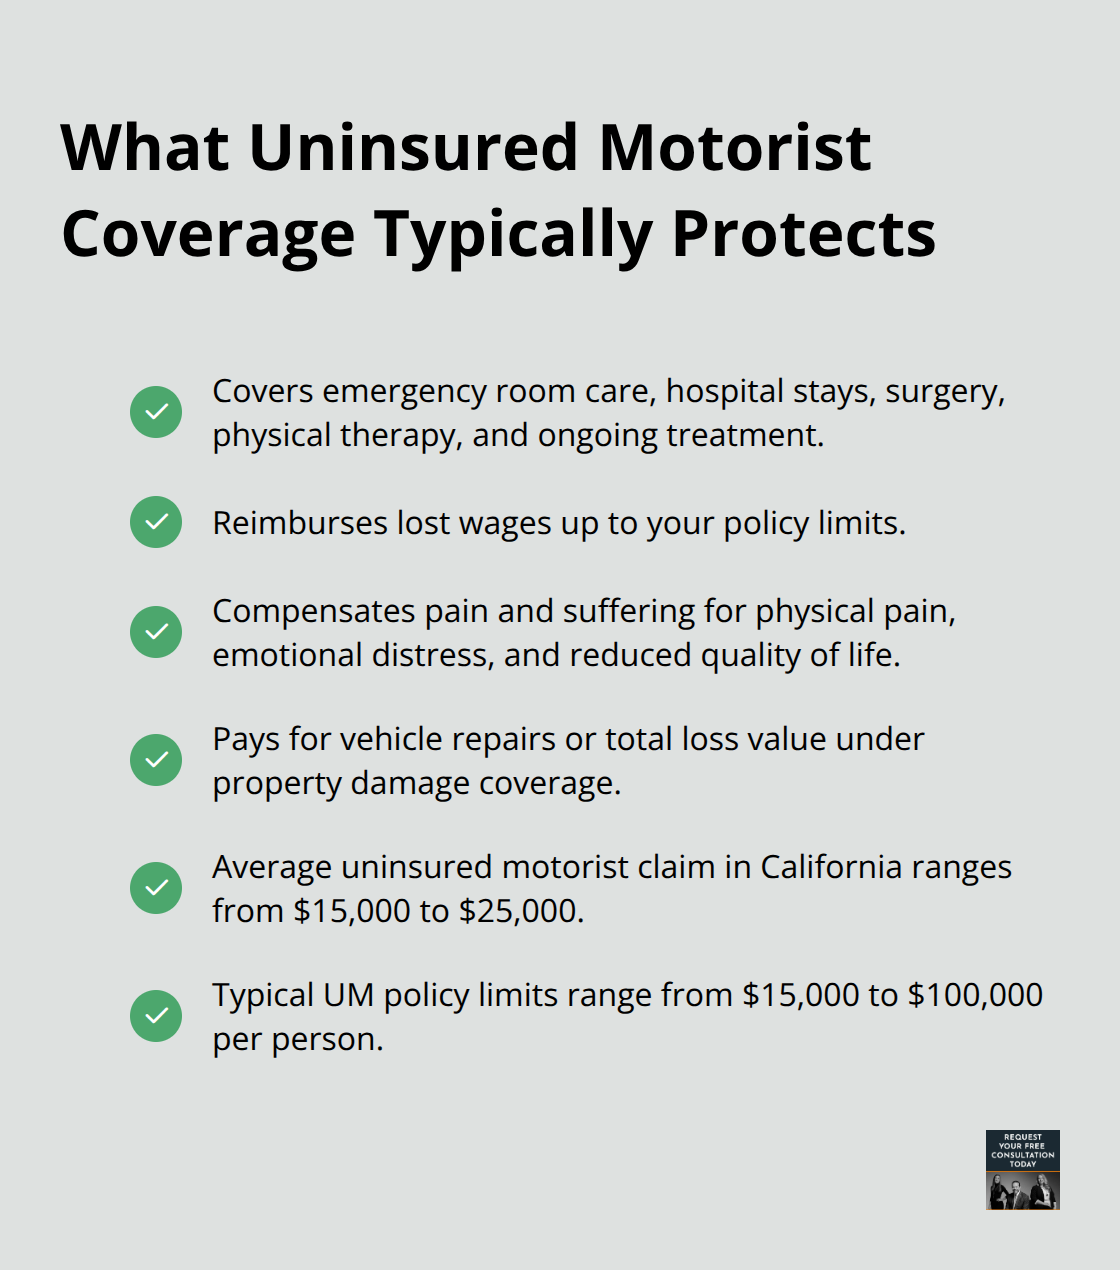
The National Association of Insurance Commissioners reports that the average uninsured motorist claim in California ranges from 15,000 to 25,000 dollars, though this varies significantly based on injury severity and policy limits. Most Santa Cruz residents carry policy limits between 15,000 and 100,000 dollars per person, which determines the maximum your insurer will pay.
Medical Expenses and Lost Wages
Medical expenses form the foundation of most uninsured motorist claims in Santa Cruz County. You should track every treatment you receive, including chiropractor visits, mental health counseling, and prescription medications, as these all count toward your claim. Your insurance company will request itemized medical records and bills, so you need to gather these systematically after your accident. If you incurred 8,000 dollars in medical costs but your injuries prevent you from working for two months at a 3,500 dollar monthly salary, your claim encompasses both the medical expenses and the 7,000 dollars in lost income.
Pain and Suffering Damages
Pain and suffering damages typically range from one to five times your actual economic damages, depending on injury severity and how the accident affected your daily functioning. Insurance adjusters calculate these damages by examining your medical records, treatment duration, and the permanent effects your injuries caused. The more severe your injuries and the longer your recovery takes, the higher your pain and suffering award becomes. You should document how the accident impacted your ability to work, exercise, spend time with family, or perform household tasks (these details strengthen your claim significantly).
Property Damage Recovery
Your uninsured motorist property damage coverage pays for vehicle repairs or the actual cash value of your vehicle if it’s totaled. You’ll need repair estimates from qualified mechanics and documentation of your vehicle’s condition before the accident. Insurance companies often dispute repair costs, so obtaining multiple estimates protects your interests. If your vehicle is worth 12,000 dollars and repairs cost 8,500 dollars, your insurer pays the repair amount rather than the vehicle’s full value.
Moving Forward With Your Claim
Calculating these damages accurately prevents you from undervaluing your claim or leaving compensation on the table. The next section walks you through the specific steps you must take immediately after an accident and how to work with your insurance company to build a strong claim.
How to File Your Claim After an Uninsured Driver Hits You
Immediate Actions at the Accident Scene
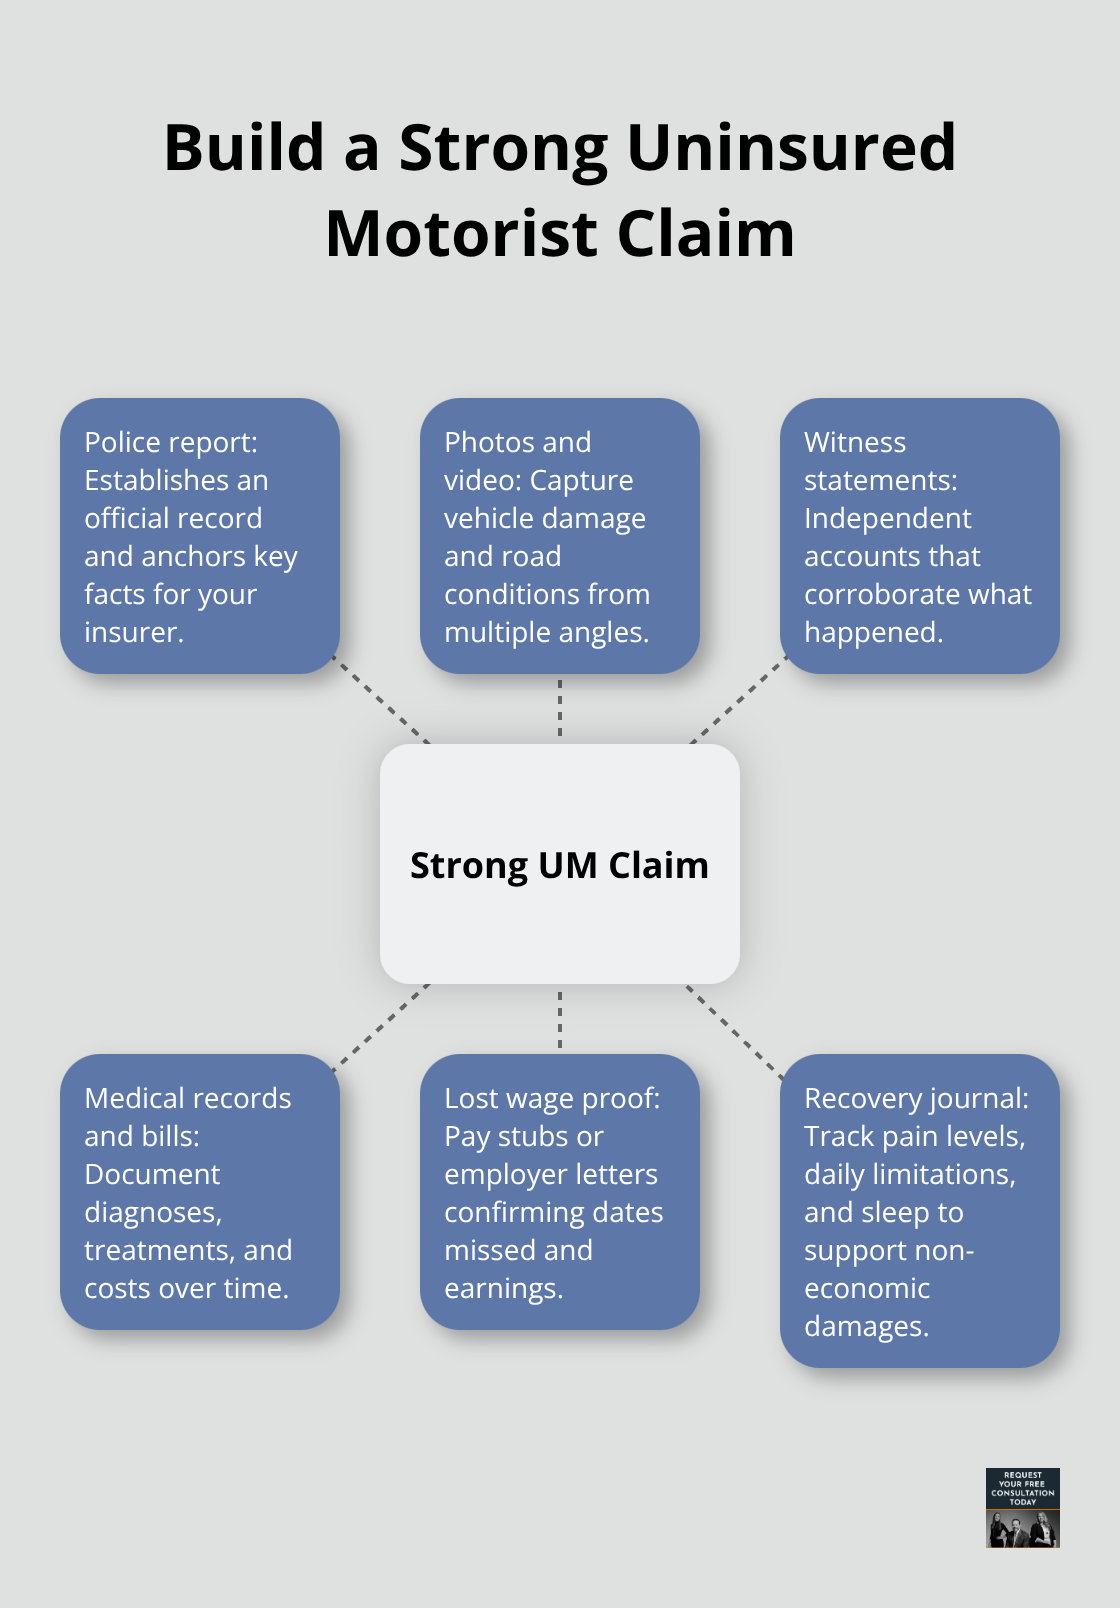
The first hours after an accident determine the strength of your uninsured motorist claim. Call the police immediately and request an official accident report, which creates a documented record that insurers require. Take photographs of vehicle damage, road conditions, and the other driver’s vehicle from multiple angles before anything moves. Obtain the other driver’s name, phone number, address, and vehicle information, but do not discuss fault or accept blame for the accident. If witnesses are present, collect their names and phone numbers right then-witness contact information becomes harder to obtain later, and the Insurance Information Institute reports that witness statements strengthen claims by an average of 18 percent.
Medical Documentation and Treatment
Seek medical attention even if you feel fine, because some injuries like whiplash or internal injuries appear hours or days after impact. Your medical records create the foundation for your entire claim, so documentation starting immediately matters more than you might think. Gather all medical records, bills, and receipts as treatment progresses, organizing them chronologically so your adjuster can review the full scope of your injuries. Track every treatment you receive, including chiropractor visits, mental health counseling, and prescription medications, as these all count toward your claim.
Notifying Your Insurance Company
Contact your insurance company within 24 hours and report the accident clearly, providing the police report number and witness information. Do not minimize your injuries or assume anything is minor-describe all symptoms you experienced, even if they seemed insignificant at the time. Request a claims adjuster assignment and ask specifically how long the claims process typically takes in Santa Cruz County.
Building Your Compensation Record
Document lost wages through pay stubs or employer letters confirming the dates you missed work and your hourly rate. Insurance companies often undervalue pain and suffering damages, so maintain a detailed journal describing how the accident affected your daily activities, sleep quality, and emotional state throughout your recovery (this documentation proves invaluable during settlement negotiations). The longer your treatment continues and the more thoroughly you document its impact on your life, the stronger your position becomes when negotiating final compensation. We at Schaar & Silva LLP help Santa Cruz residents navigate these claims by ensuring nothing gets overlooked and that insurers offer fair settlements rather than initial lowball figures designed to close cases quickly.
Final Thoughts
An uninsured motorist collision in Santa Cruz disrupts your life financially and physically, leaving you to navigate medical bills, vehicle repairs, and lost income on your own. You now understand that roughly one in seven drivers on local roads lacks insurance, that your uninsured motorist coverage protects medical expenses, lost wages, and pain and suffering damages, and that documenting everything immediately after an accident strengthens your claim significantly. The statistics are clear, the coverage details matter, and the filing process demands attention to detail.
Some claims settle quickly when documentation is thorough and injuries are straightforward, while others require negotiation because insurance adjusters frequently offer settlements below what your claim actually warrants. The difference between accepting an initial offer and pursuing fair compensation often reaches thousands of dollars, which is why having someone review your case makes genuine financial sense. Insurance companies operate with specific procedures and documentation requirements that vary by situation, and understanding these details protects your interests throughout the process.
Contact Schaar & Silva LLP to discuss your uninsured motorist Santa Cruz claim and injuries. A consultation clarifies what your coverage actually protects in your situation and identifies compensation you might otherwise miss. The sooner you reach out, the sooner we can begin protecting your interests and building the strongest possible claim.