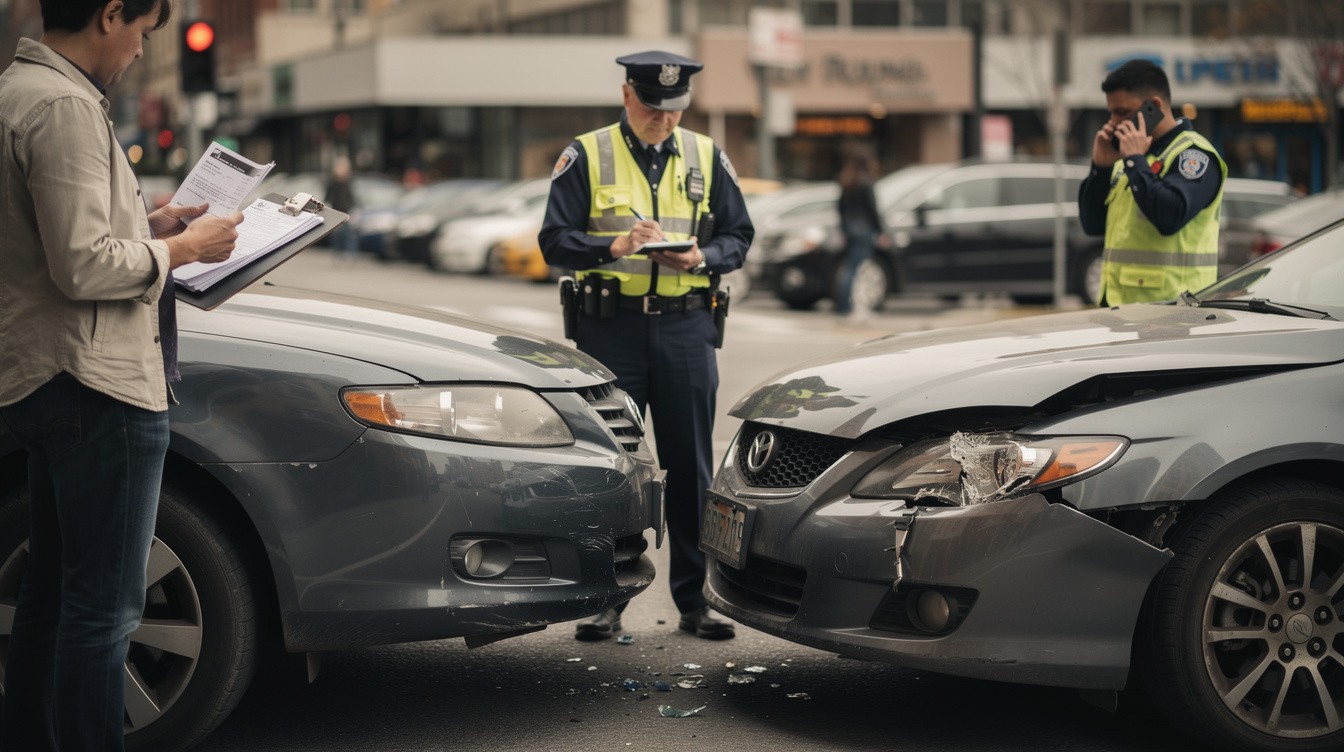
A car accident with an uninsured motorist in Santa Cruz can leave you confused about what happens next. You might wonder if you’re protected, what compensation you can claim, and how to move forward.
We at Schaar & Silva LLP know these situations are stressful. This guide walks you through your rights, your coverage options, and the concrete steps to take after an uninsured motorist accident.
Who Counts as an Uninsured Motorist in Santa Cruz
Definition and Legal Requirements
An uninsured motorist is someone driving without active liability insurance or with coverage limits so low they cannot cover your damages. California law requires drivers to carry a minimum of $15,000 in bodily injury liability per person and $30,000 per accident, according to California Department of Insurance requirements. Despite this legal mandate, uninsured drivers remain a serious problem in Santa Cruz County.
The Scale of the Problem
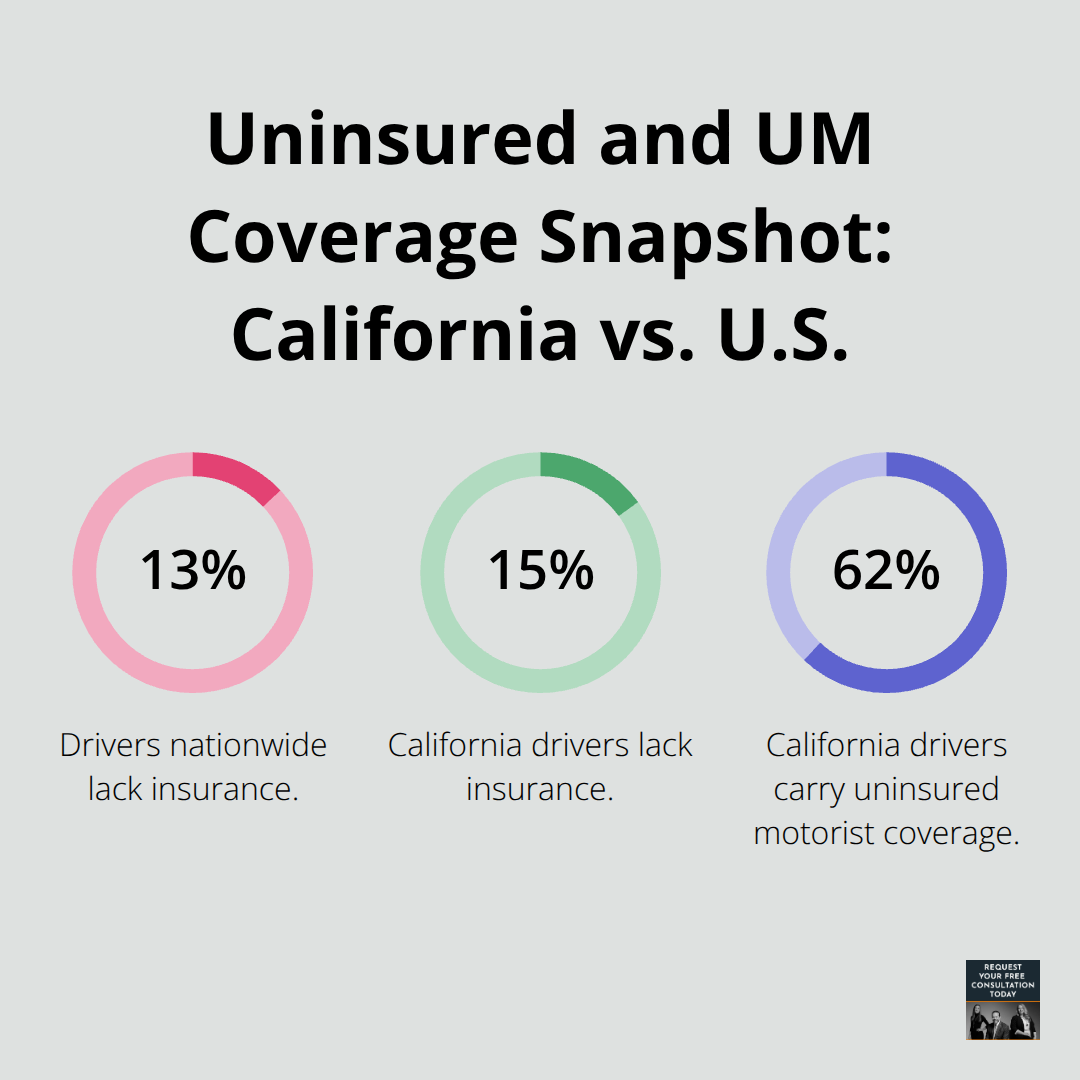
The National Association of Insurance Commissioners reports that roughly 13 percent of drivers nationwide lack insurance, and California’s uninsured rate hovers around 15 percent-meaning one in seven drivers on Santa Cruz roads may be uninsured or underinsured. An underinsured motorist has insurance but their policy limits fall short of covering your actual losses, which creates a gap you may need to fill through your own coverage.
How Uninsured Claims Differ from Standard Accidents
When an uninsured motorist hits you, your claim process differs significantly from standard accidents. With an insured driver, you file a claim against their liability policy and their insurance company handles the defense and payment. With an uninsured motorist, you must turn to your own uninsured motorist coverage, which acts as a safety net. This shift means your own insurance company becomes your advocate, but you’re working within your own policy limits rather than pursuing the at-fault driver’s deeper pockets.
What You’ll Need to Prove
The uninsured motorist claim typically takes longer because your insurer must investigate whether the other driver was truly uninsured and determine fault independently. You’ll need solid evidence from the accident scene, police reports, and medical documentation to support your claim. Many Santa Cruz residents discover too late that they skipped uninsured motorist coverage to save money on premiums, only to find themselves severely underprotected after an accident.
Understanding these differences prepares you for what lies ahead. Your next step involves learning what coverage options actually protect you and what rights California law grants you in this situation.
Your Coverage and Rights After an Uninsured Motorist Accident
Understanding Your Uninsured Motorist Coverage
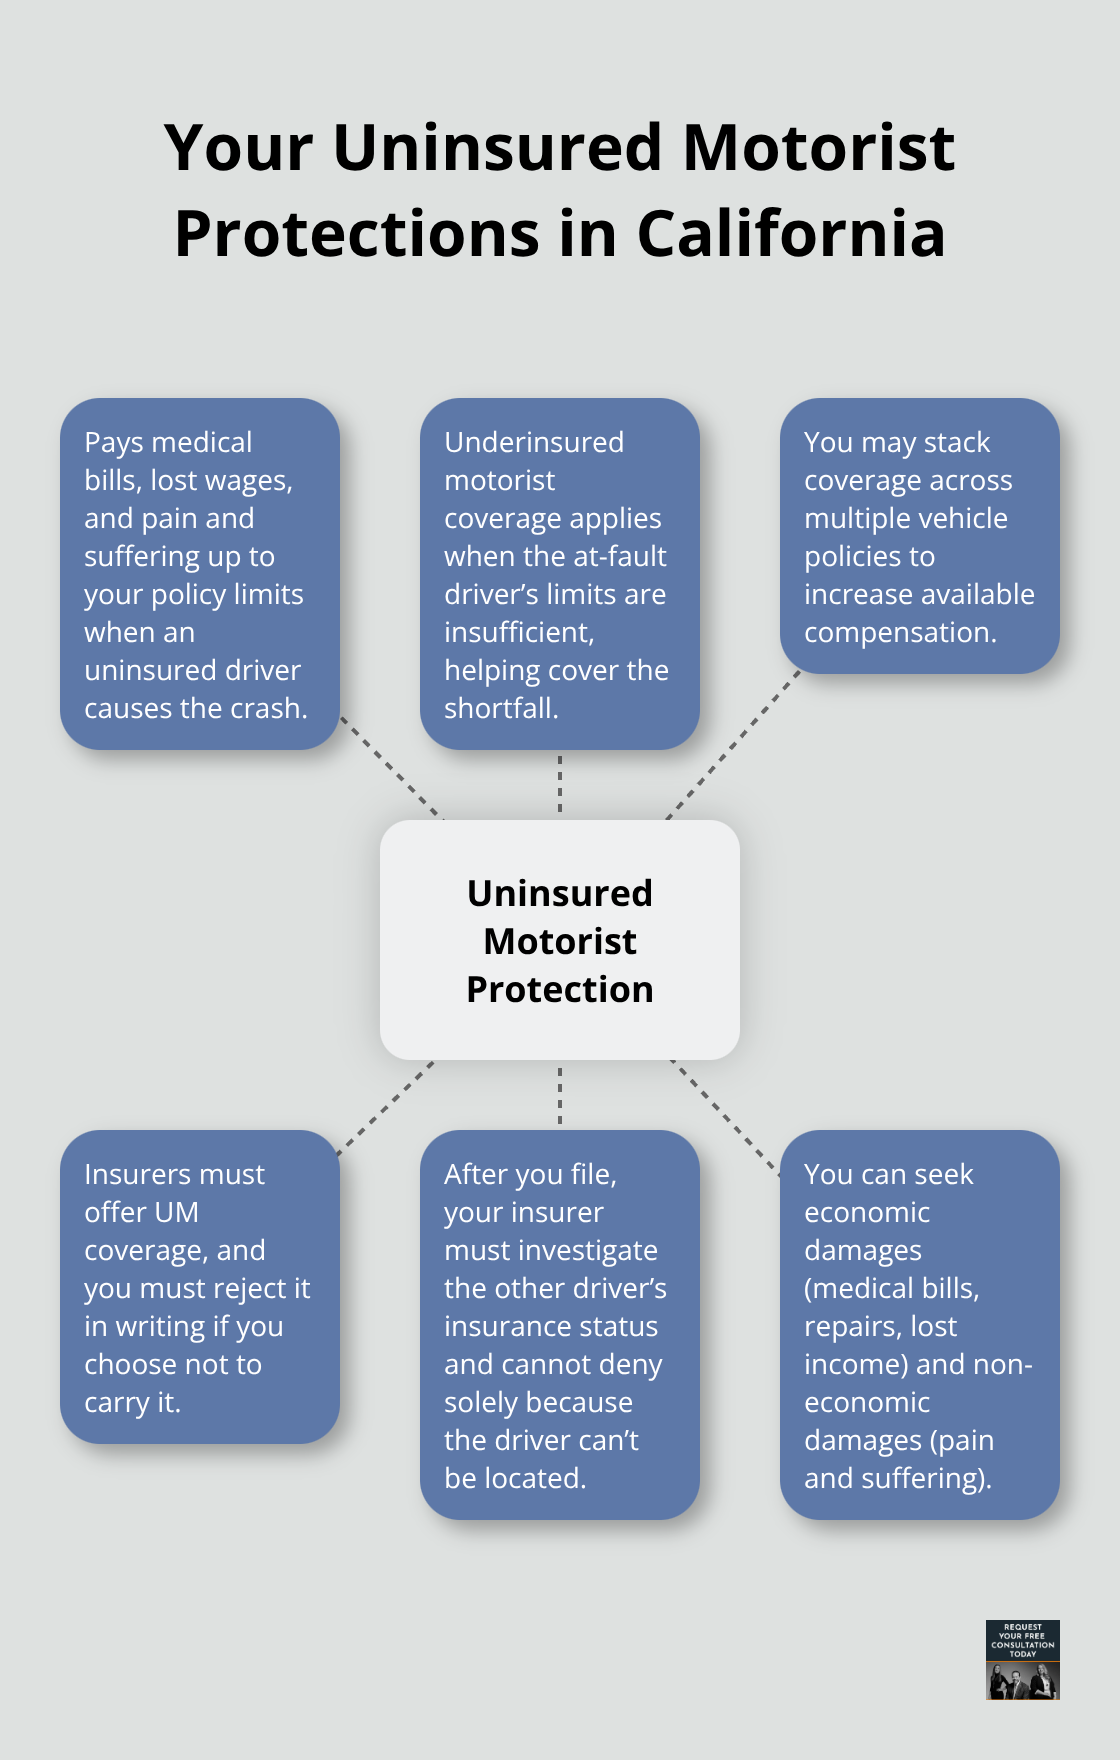
Your policy likely contains uninsured motorist bodily injury coverage, which California law requires insurers to offer. This coverage pays your medical bills, lost wages, and pain and suffering up to your chosen limit when an uninsured driver causes the accident. Most Santa Cruz residents carry between $15,000 and $100,000 in uninsured motorist limits, though this varies widely. The California Department of Insurance reports that only about 62 percent of drivers in California carry uninsured motorist coverage, leaving far too many people vulnerable.
Your coverage limit determines your maximum recovery through this avenue. If you have $50,000 in coverage and your damages total $80,000, you can only recover $50,000 through uninsured motorist protection. Underinsured motorist coverage works similarly but applies when the at-fault driver’s insurance limits fall short of your actual losses. This distinction matters because it determines whether you tap your own policy or pursue the other driver’s insufficient coverage first.
Stacking Coverage and Maximizing Protection
California law allows you to stack coverage if you own multiple vehicles, meaning you can combine limits across policies to reach higher compensation totals. This option significantly increases your protection without requiring additional premiums in most cases. Many Santa Cruz residents discover too late that they skipped uninsured motorist coverage to save money on premiums, only to find themselves severely underprotected after an accident.
Your Legal Rights Under California Law
California Vehicle Code Section 16056 mandates that insurers offer uninsured motorist protection, and you must actively reject it in writing if you choose not to carry it. Once you file a claim, your insurer must investigate the other driver’s insurance status and cannot deny your claim simply because they cannot locate the uninsured motorist. You have the right to compensation for economic damages like medical expenses, vehicle repairs, and lost income, plus non-economic damages for pain and suffering.
California courts have awarded uninsured motorist claimants substantial settlements when medical evidence and lost wage documentation are strong. The at-fault driver’s liability does not disappear just because they lacked insurance, which means you could potentially pursue a judgment against them personally after your insurance claim concludes.
Getting Help with Medical Bills
Medical lien services can facilitate payment of your bills until your case resolves, allowing you to focus on recovery rather than immediate out-of-pocket costs. This approach removes the financial pressure while your claim moves forward. With these protections and rights in place, your next move involves taking concrete action immediately after the accident occurs.
What to Do Immediately After an Uninsured Motorist Accident
Document the Scene Thoroughly
The first few hours after an accident determine how strong your claim becomes. Police reports, witness statements, and scene documentation create the foundation that insurers and attorneys rely on to process your claim. At the accident scene, photograph everything from multiple angles, including vehicle damage, skid marks, road conditions, and the surrounding area.
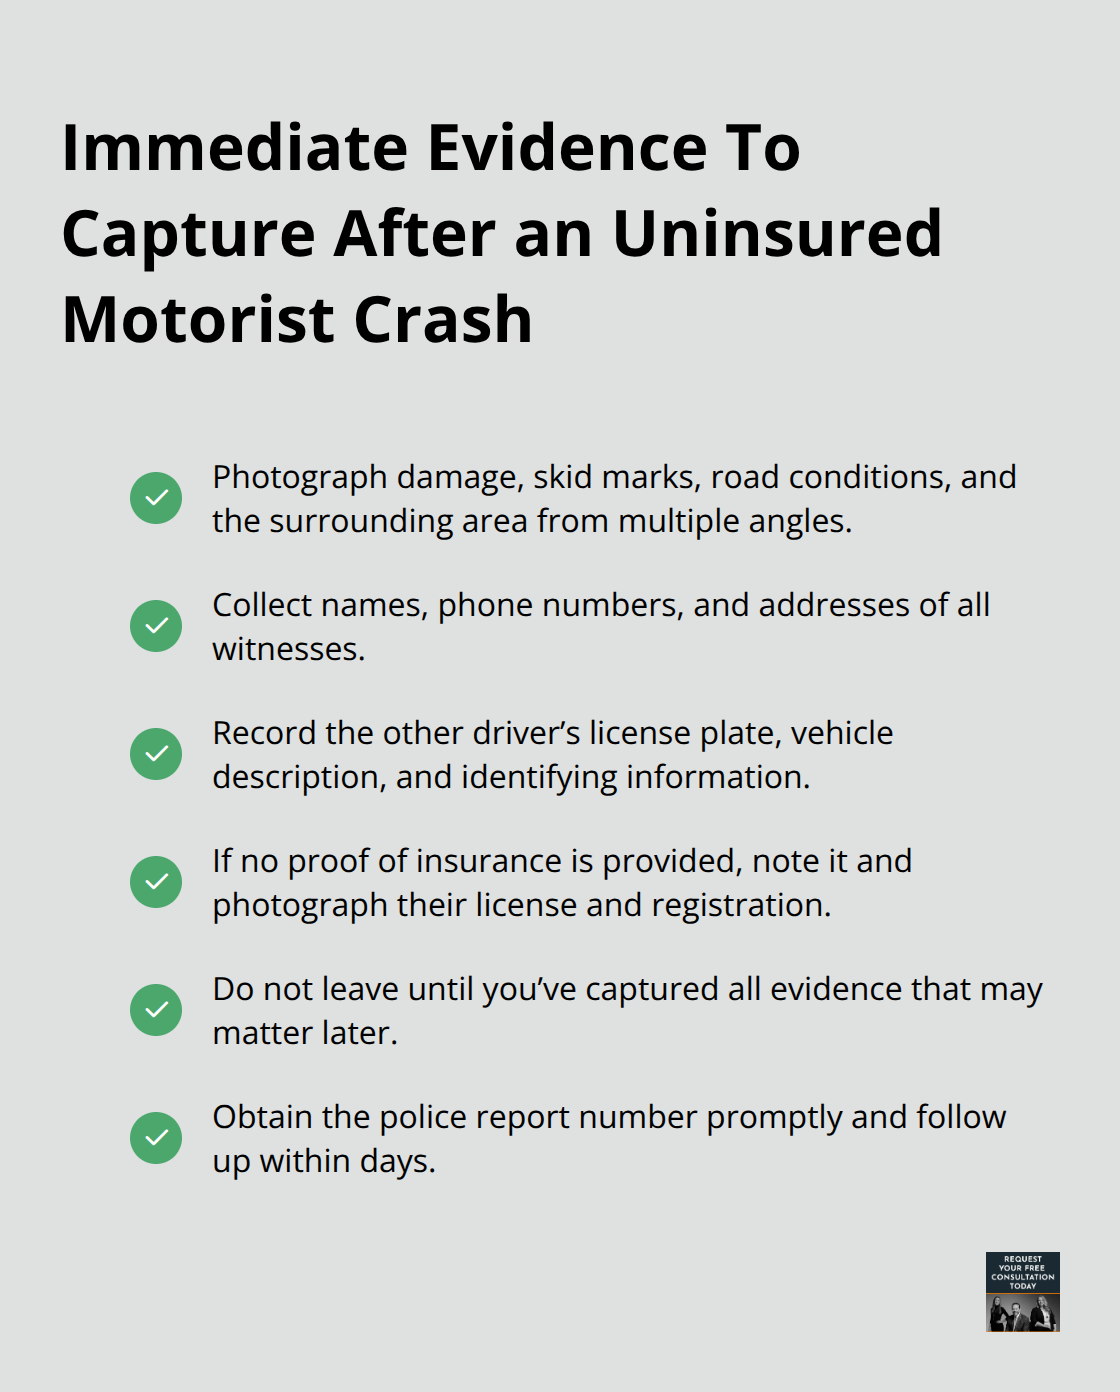
Get the names, phone numbers, and addresses of all witnesses, not just their verbal accounts. Write down the other driver’s license plate number, vehicle description, and any identifying information.
If the other driver cannot produce proof of insurance, note that explicitly and photograph their license and vehicle registration. Nearly 40 percent of uninsured motorist claims face delays because claimants failed to gather adequate scene documentation. Do not leave the scene until you have photographed or video-recorded everything that might matter later.
File a Police Report and Notify Your Insurer
Contact local police to file an official accident report, which becomes your claim’s most credible piece of evidence. Obtain the report number and follow up within days to verify the police documented the uninsured status. Call your insurance company within 24 hours and report the accident, providing all details and the police report number. This immediate notification protects your claim and starts the investigation process.
Seek Medical Attention and Preserve Records
Medical attention should happen immediately, even if you feel fine, because some injuries emerge days or weeks later (and insurance companies scrutinize gaps between accident and treatment). Keep every receipt, medical record, prescription, and communication about your injuries. This documentation directly supports your compensation claim and prevents insurers from questioning the severity of your condition.
Get Legal Guidance Before Settling
Contact an attorney before accepting any settlement offer, as insurers often propose amounts far below what you actually deserve, particularly when medical expenses and lost wages accumulate over time. The legal team at Schaar & Silva LLP can review your case and help you understand what fair compensation looks like for your specific situation. With proper legal guidance, you protect yourself from accepting inadequate offers that leave you financially short.
Final Thoughts
An uninsured motorist accident in Santa Cruz leaves you facing financial and legal challenges that standard claims don’t create. California law grants you specific protections through uninsured motorist coverage, your own policy becomes your primary resource, and compensation for medical expenses, lost wages, and pain and suffering remains within reach. The path forward requires immediate action-you must document the scene, file police reports, seek medical care, and preserve every record that supports your claim.
Insurance companies know that uninsured motorist Santa Cruz claims involve complexity, and they count on claimants handling these cases alone. The difference between recovering fair compensation and accepting inadequate settlement offers often comes down to legal guidance. When you work with Schaar & Silva LLP, you gain someone who understands California’s uninsured motorist laws, knows what your case is actually worth, and can negotiate with insurers from a position of strength.
Contact Schaar & Silva LLP to discuss your case before accepting any settlement offer. The consultation helps you understand exactly what your claim is worth and what options exist for moving forward. You don’t have to navigate this alone, and waiting too long can cost you thousands in lost compensation.