
A car accident in Santa Cruz County can turn your life upside down, especially when the at-fault driver doesn’t carry enough insurance to cover your medical bills and vehicle repairs.
Standard liability coverage often leaves accident victims short, which is why underinsured motorist Santa Cruz protection exists. We at Schaar & Silva LLP help residents understand this coverage and fight for the compensation they deserve.
What Is Underinsured Motorist Coverage
Underinsured motorist coverage protects you when the at-fault driver’s insurance limits fall short of your actual damages. California law requires all drivers to carry minimum liability coverage of $15,000 per person and $30,000 per accident for bodily injury, plus $5,000 for property damage. These minimums sound adequate until you face a serious accident. A single hospitalization can easily exceed $50,000, and multiple injuries push costs far higher. Your underinsured motorist coverage bridges that gap by paying the difference between what the other driver’s policy covers and your legitimate damages. This coverage is optional in California, but we at Schaar & Silva LLP strongly recommend it. Without it, you absorb the financial burden yourself, which can devastate your recovery and financial stability.
Why Standard Liability Leaves You Exposed
Standard liability insurance protects the other driver, not you. When that driver causes your accident, their policy pays your damages only up to their limits. According to the Insurance Information Institute, the average cost of a serious injury claim reaches $75,000 or more. Most drivers in Santa Cruz County carry only minimum coverage, meaning you face a significant shortfall. Medical expenses, lost wages, vehicle repairs, and pain and suffering add up quickly in real accidents.
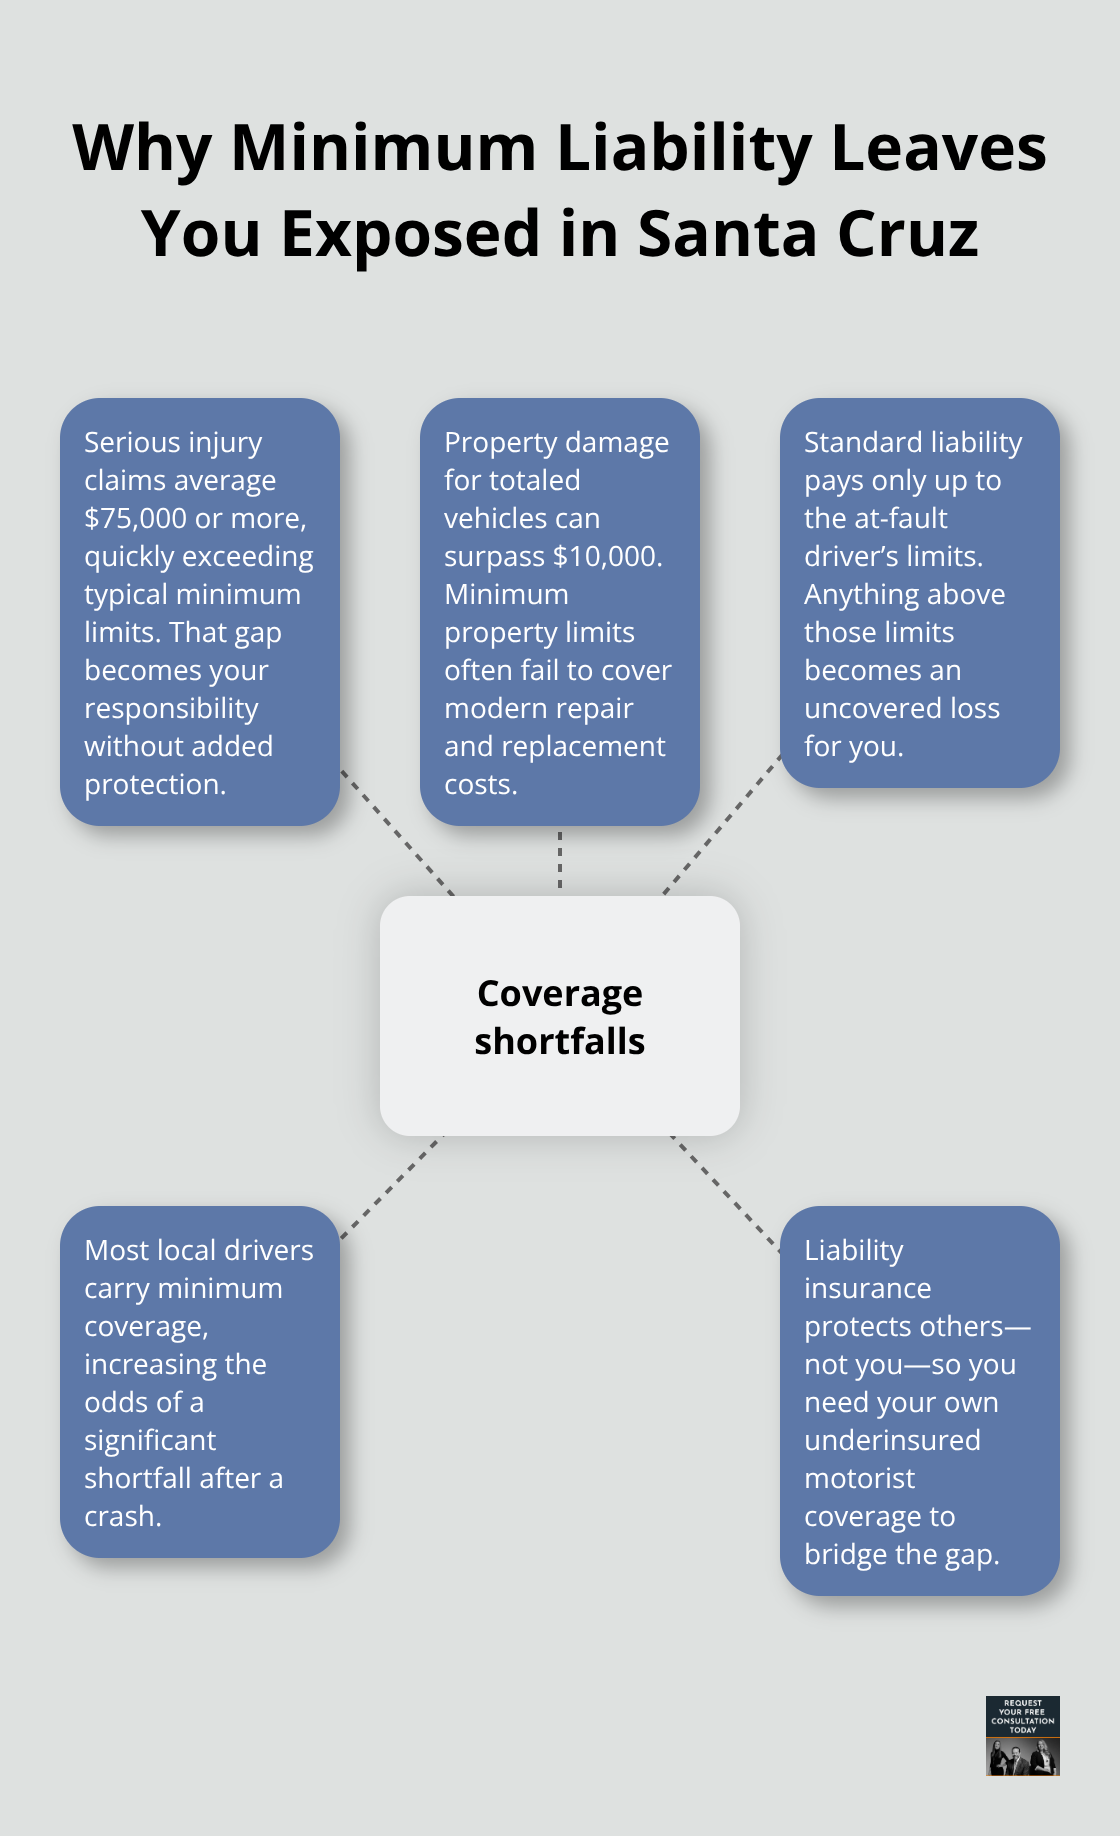
Property damage claims alone can exceed $10,000 for totaled vehicles. Without underinsured motorist coverage, you cannot recover these excess costs from anyone. The at-fault driver has no financial incentive to carry higher limits, so you must protect yourself. This is not theoretical-Santa Cruz County residents face this reality constantly after accidents.
How Your Coverage Actually Works
When you file an underinsured motorist claim, your own insurance company pays you the difference between their coverage and the at-fault driver’s policy limits. The process requires clear documentation of your damages and proof that the other driver was at fault. Your insurance adjuster investigates, reviews medical records, repair estimates, and other evidence. The payout covers medical bills, lost income, vehicle damage, and compensation for pain and suffering. California law allows you to recover up to your policy limits. Many people mistakenly believe their health insurance or the other driver’s policy will cover everything, but gaps remain. The legal team at Schaar & Silva LLP helps Santa Cruz residents navigate these claims and fight for full compensation when insurers undervalue their damages.
What Happens When You File a Claim
Filing an underinsured motorist claim involves several concrete steps. First, you report the accident to your insurance company and provide all relevant documentation (medical records, repair estimates, proof of lost wages). Your insurer then investigates whether the at-fault driver’s coverage truly falls short of your damages. This investigation determines whether your claim qualifies for underinsured motorist protection. The insurance company makes an offer based on their assessment of your damages. If you disagree with their valuation, you have the right to negotiate or pursue further action. Many Santa Cruz residents find that professional guidance during this stage protects their interests and increases their recovery amount.
When Underinsured Motorist Coverage Actually Matters
The Real Cost of Minimum Coverage
The gap between what an at-fault driver’s insurance covers and your actual damages becomes painfully real when medical bills and repair invoices arrive. In Santa Cruz County, most drivers carry only the state minimum of $15,000 per person for bodily injury. A single emergency room visit with imaging, surgery, and follow-up care reaches $30,000 to $50,000.
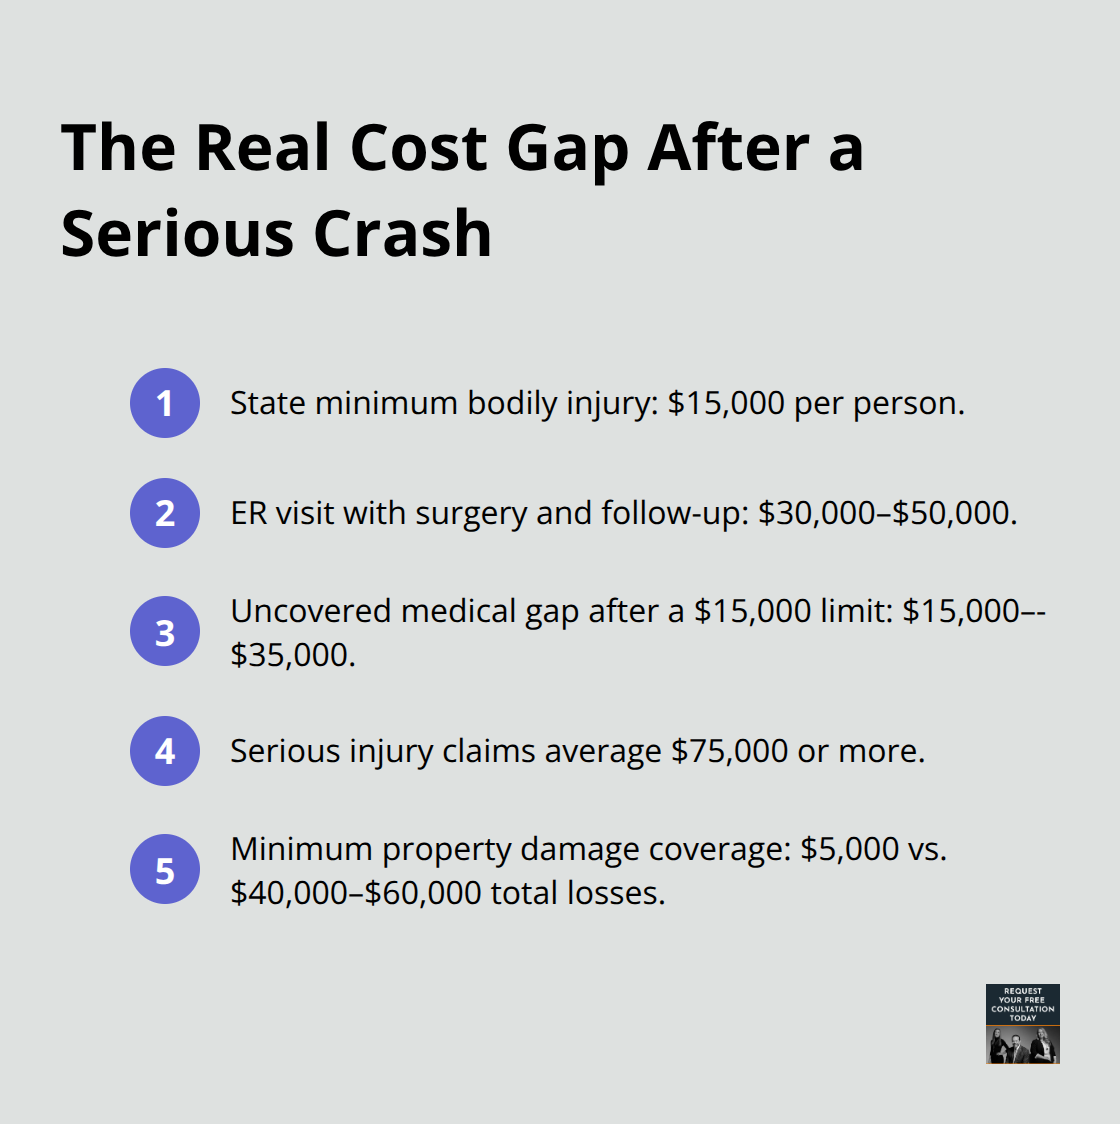
When a driver causes your accident and their policy maxes out at $15,000, you absorb the remaining $15,000 to $35,000 yourself without underinsured motorist coverage. The Insurance Information Institute reports that serious injury claims average $75,000 or more, making the gap catastrophic for unprotected drivers.
Vehicle Damage and Multiple Injuries Compound the Problem
Vehicle totals create another massive shortfall. A newer SUV or truck totals at $40,000 to $60,000, yet minimum property damage coverage only reaches $5,000. You lose $35,000 to $55,000 in vehicle value with no recovery option. Multiple people injured in the same accident multiply these shortfalls dramatically. Two injured passengers mean two separate $15,000 policy limits that vanish within hours of hospitalization. Three injured passengers exhaust a $30,000 per-accident limit almost immediately.
Lost Wages and Pain and Suffering
Lost wages during recovery add another financial layer. If you earn $60,000 annually and miss three months of work, that amounts to $15,000 in income you cannot recover from the at-fault driver’s minimal policy. Pain and suffering compensation, which California law recognizes as legitimate damages, receives no protection under their liability limits. These scenarios occur constantly in Santa Cruz County accidents, leaving victims financially devastated while the at-fault driver faces no consequence for carrying inadequate coverage.
How Your Underinsured Motorist Coverage Protects You
Your underinsured motorist coverage bridges these real gaps with your own policy limits. If you carry $100,000 in underinsured motorist protection and the at-fault driver has $15,000 coverage, your policy pays up to $85,000 more for your legitimate damages. The key word is legitimate. You must prove your damages through medical records, repair estimates, wage documentation, and other concrete evidence. Insurance companies scrutinize these claims aggressively, often undervaluing pain and suffering or disputing the necessity of certain treatments.
Getting Professional Help With Your Claim
This is where professional guidance protects your recovery. The legal team at Schaar & Silva LLP helps Santa Cruz residents document damages thoroughly and negotiate with insurance companies when their initial offers fall short of reality. Our team can also direct you to medical lien services that facilitate the payment of your bills until your case is resolved, allowing you to focus on healing rather than financial stress. Without this coverage and proper representation, you carry the entire financial weight of someone else’s inadequate insurance-but the next section shows you exactly how to file a claim and fight for what you deserve.
How to File an Underinsured Motorist Claim in Santa Cruz County
Act Quickly After Your Accident
The moments immediately after an accident determine how successfully you’ll recover compensation. Contact your insurance company within 24 to 48 hours, not weeks later. Most policies require prompt notification, and delays give insurers grounds to deny claims. When you call, stick to the facts: date, time, location, who was involved, and basic descriptions of what happened. Do not admit fault or speculate about injuries.
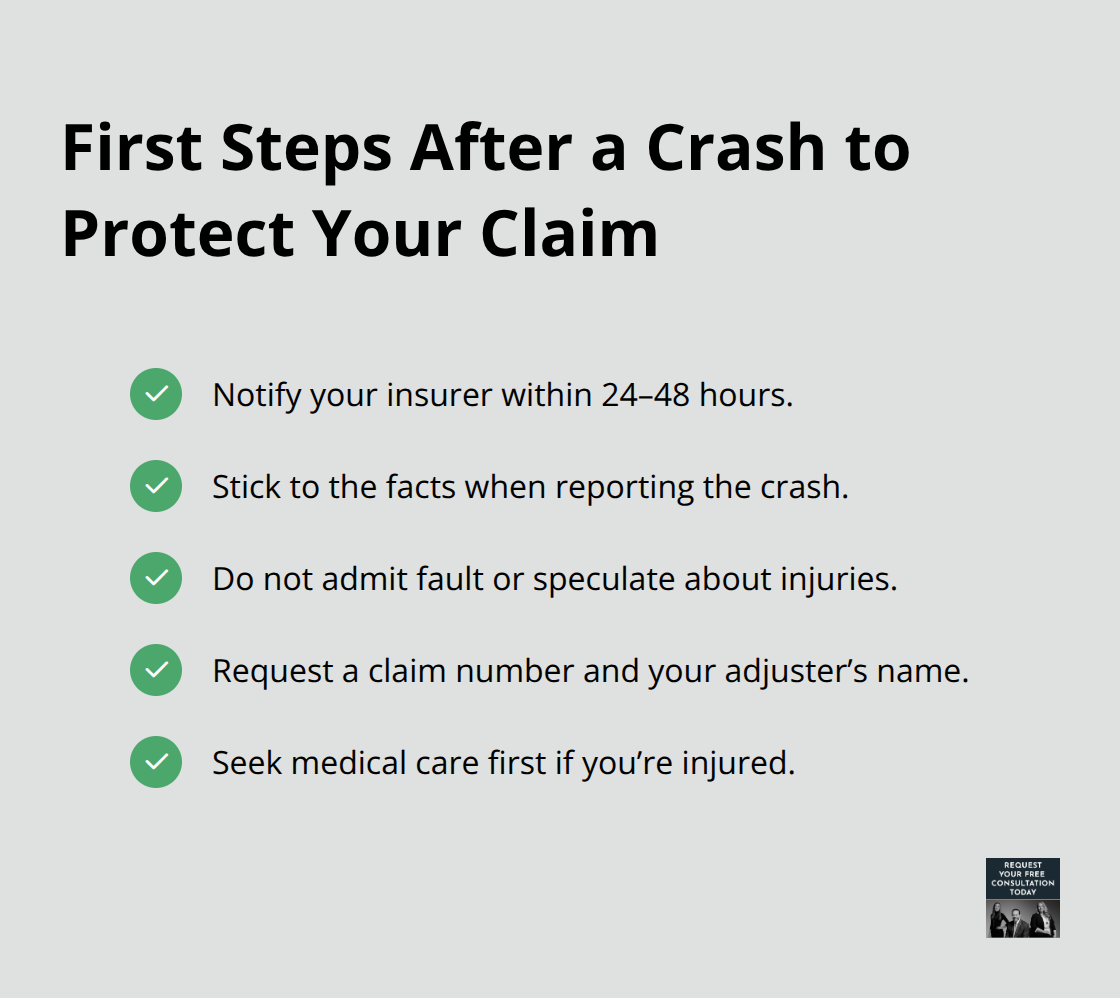
Request a claim number and the name of your adjuster. If you’re injured, seek medical attention first, then handle the insurance call.
Collect Evidence at the Scene
Save every document from this point forward: police reports, medical records, repair estimates, photos of vehicle damage, and receipts for expenses related to the accident. The Insurance Institute for Highway Safety notes that documented claims resolve faster and result in higher payouts than those lacking evidence. Take photos of the accident scene, vehicle damage, and road conditions if you’re physically able. Get the other driver’s insurance information, license plate number, and contact details. If witnesses were present, collect their names and phone numbers. Many Santa Cruz residents skip this step and regret it later when insurers question claim details.
Build Your Documentation File
Documentation separates successful claims from rejected ones. Gather medical records showing all treatment related to your injuries, including emergency room visits, follow-up appointments, imaging results, and prescribed medications. Insurance adjusters scrutinize medical necessity intensely, so obtain detailed bills and explanations of services from every provider. For vehicle damage, obtain written repair estimates from at least two shops and photos showing the damage. If your vehicle is totaled, get a valuation report from a reputable source like NADA Guides or Kelley Blue Book.
Document lost wages with pay stubs, tax returns, and a letter from your employer confirming the dates you missed work and hourly rate. Keep receipts for transportation costs, childcare expenses while recovering, or other accident-related spending. Insurance companies undervalue pain and suffering claims routinely, so create a detailed timeline of how your injuries affected daily activities: inability to work, physical therapy sessions, medication side effects, and lifestyle changes. Write these details while they’re fresh, not months later.
Challenge Lowball Settlement Offers
When your insurance company makes an initial offer, request a detailed breakdown of how they calculated each component. If their numbers don’t match your documented damages, challenge them specifically with evidence rather than general complaints. The legal team at Schaar & Silva LLP helps Santa Cruz residents evaluate insurance offers and negotiate for fair settlements when adjusters undervalue legitimate claims. Our team can also direct you to medical lien services that manage your medical bills during the claims process, eliminating the stress of mounting healthcare costs while waiting for resolution.
Final Thoughts
Underinsured motorist Santa Cruz protection isn’t optional if you want financial security after an accident. Most drivers in Santa Cruz County carry minimum liability coverage that evaporates within hours of serious injury treatment, leaving you responsible for medical bills, vehicle damage, lost wages, and pain and suffering costs that far exceed their policy limits. Without your own underinsured motorist coverage, you absorb thousands or tens of thousands of dollars in losses through no fault of your own.
Evaluating your current coverage takes one phone call to your insurance agent-ask specifically about your underinsured motorist limits and whether they match your actual financial exposure. If you carry significant home equity or own a vehicle worth $40,000, your underinsured motorist coverage should reflect that reality. Most Santa Cruz residents discover their coverage is inadequate only after an accident occurs, which is far too late to make changes.
The team at Schaar & Silva LLP helps Santa Cruz residents navigate underinsured motorist claims from start to finish, challenging insurance company offers with documented evidence and connecting you with medical lien services that manage your bills during the claims process. If you’ve been in an accident and face an insurance company that won’t pay fairly, contact us to discuss your situation and learn how we can help you recover what you deserve.
