A car accident with an underinsured driver leaves you facing a gap between your damages and what their insurance will cover. That’s where underinsured motorist coverage steps in to bridge that gap and protect your recovery.
At Schaar & Silva LLP, we help accident victims in Santa Cruz County, Sacramento, and Oakland navigate underinsured motorist claims when they face this exact situation. This guide walks you through the process, the obstacles you’ll encounter, and how to strengthen your position.
Understanding Underinsured Motorist Coverage
What UIM Coverage Actually Protects
Underinsured motorist coverage fills a gap that standard liability insurance leaves wide open. When the at-fault driver carries minimal coverage-California’s minimum is $15,000 per person for bodily injury-their insurance often runs dry long before your medical bills and lost wages are covered. Your UIM coverage then steps in to cover the difference between what their policy pays and your actual damages, up to your policy limit. This matters tremendously in Santa Cruz County, where coastal highway accidents involving tourists and commuters frequently result in severe injuries. The California Department of Motor Vehicles reports that Santa Cruz County averaged over 8,000 traffic collisions annually in recent years, and many drivers carry only the state minimum. Without UIM protection, you absorb those uncovered costs yourself, potentially facing tens of thousands in unpaid medical expenses and lost income.
How UIM Differs From Uninsured Motorist Coverage
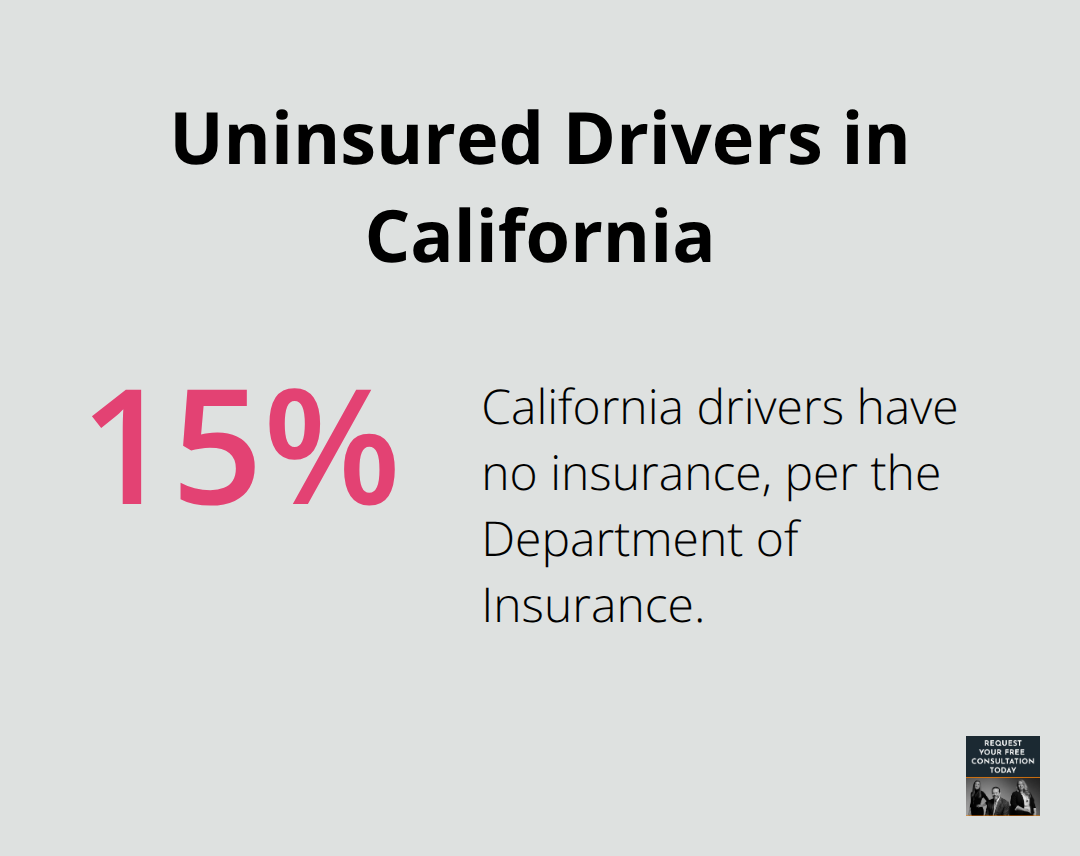
UIM coverage operates fundamentally differently from uninsured motorist coverage, though many people confuse them. Uninsured motorist protection applies when the at-fault driver has zero insurance-a scenario affecting roughly 15% of California drivers according to the California Department of Insurance. UIM activates when the driver has insurance but not enough to cover your damages.
The distinction matters because your claim process, negotiation tactics, and recovery potential shift depending on which coverage applies. In Sacramento and Oakland, where traffic density creates higher accident frequencies, understanding this difference prevents you from leaving money on the table.
Stacking Coverage Across Multiple Vehicles
You can stack UIM coverage across multiple vehicles you own, meaning if you have two cars with $250,000 UIM limits each, you could potentially recover up to $500,000 in UIM benefits-a substantial advantage when facing catastrophic injuries. Many accident victims miss these stacking opportunities simply because they don’t understand their policy’s structure. The next section walks you through the specific steps that transform your understanding into action.
How to File Your UIM Claim
Start Your Claim Immediately After Treatment
Contact your insurance company within 30 days of the accident-most California policies require prompt notice, and delays can jeopardize your claim. When you call, provide your policy number, the date and location of the accident, and the other driver’s insurance information. Document everything from this first conversation: the representative’s name, the time, and what they tell you about next steps.
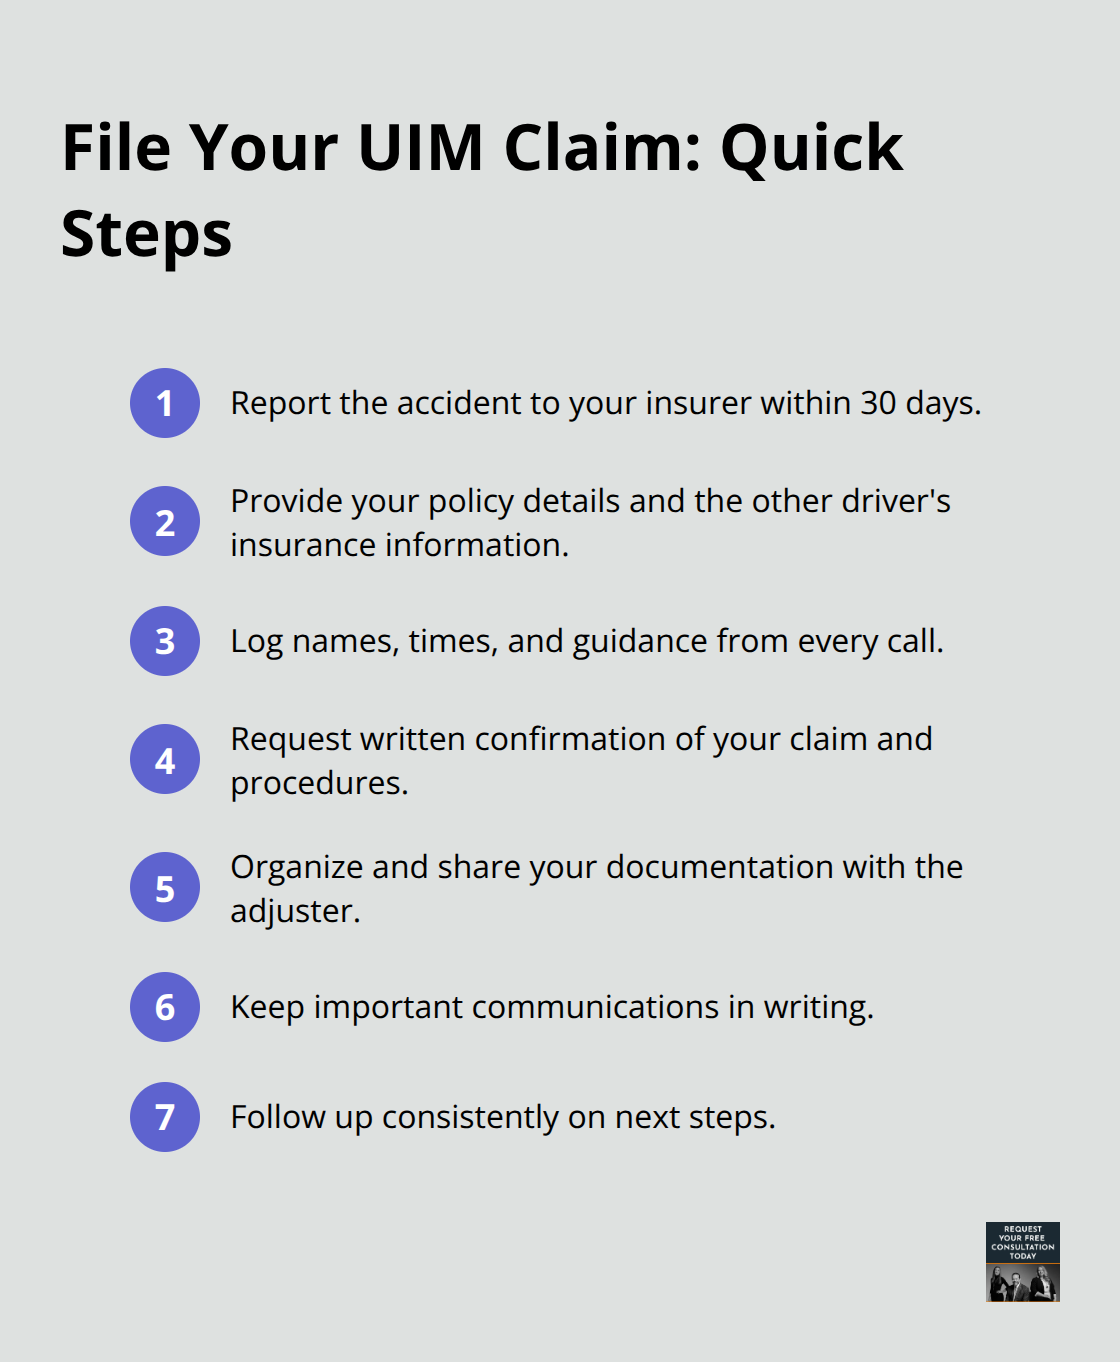
Your insurance company will assign a claims adjuster, and this person becomes central to your case. Request written confirmation of your claim filing and ask for the company’s UIM claim procedures in writing. Many insurers drag their feet on UIM claims because they cost the company money directly, so written documentation protects you from vague verbal promises or convenient memory lapses later.
Gather Medical Documentation and Bills
Medical records form the foundation of your damage claim. Collect your medical bills, pharmacy receipts, physical therapy invoices, and any mental health treatment expenses-the American Journal of Emergency Medicine found that accident victims with documented psychological injuries recover higher settlements. Your insurance company will scrutinize these records, so organize them chronologically and highlight treatments directly related to the accident. Include receipts for transportation to medical appointments, home modifications for accessibility, or any equipment you purchased due to your injuries. The stronger your documentation package, the harder it becomes for your insurance company to undervalue your claim.
Document Vehicle Damage and Lost Income
Photograph your vehicle damage from multiple angles and obtain a professional damage assessment from a certified appraiser, not just a body shop estimate. Calculate your lost wages by collecting pay stubs showing the income you lost during recovery, plus any reduction in earning capacity if your injuries affect your ability to work long-term. If you’re self-employed, gather tax returns and business records that demonstrate your income loss. This financial documentation carries substantial weight in settlement negotiations.
Create a Personal Injury Journal
Document non-economic damages through a journal describing your pain levels, mobility limitations, and how the accident disrupted your daily life-judges and adjusters weight detailed personal accounts heavily. Write entries consistently throughout your recovery, noting specific activities you couldn’t perform and emotional impacts you experienced. This journal transforms abstract suffering into concrete, relatable evidence that strengthens your position against the insurance company’s attempts to minimize your claim.
Prepare for the Adjuster’s Investigation
Your insurance company will investigate your claim, and the adjuster will contact you for a recorded statement. Insurance companies use these statements to identify inconsistencies or statements that limit your recovery, so answer questions carefully and stick to facts you can verify. Provide the adjuster with your documentation package proactively rather than waiting for requests-this demonstrates organization and confidence in your claim’s strength. The adjuster’s investigation findings directly influence whether your insurance company accepts your claim or disputes your damages, which leads directly into the obstacles you’ll face in the negotiation phase.
Common Obstacles in UIM Claims
Insurance Companies Undervalue Your Claim
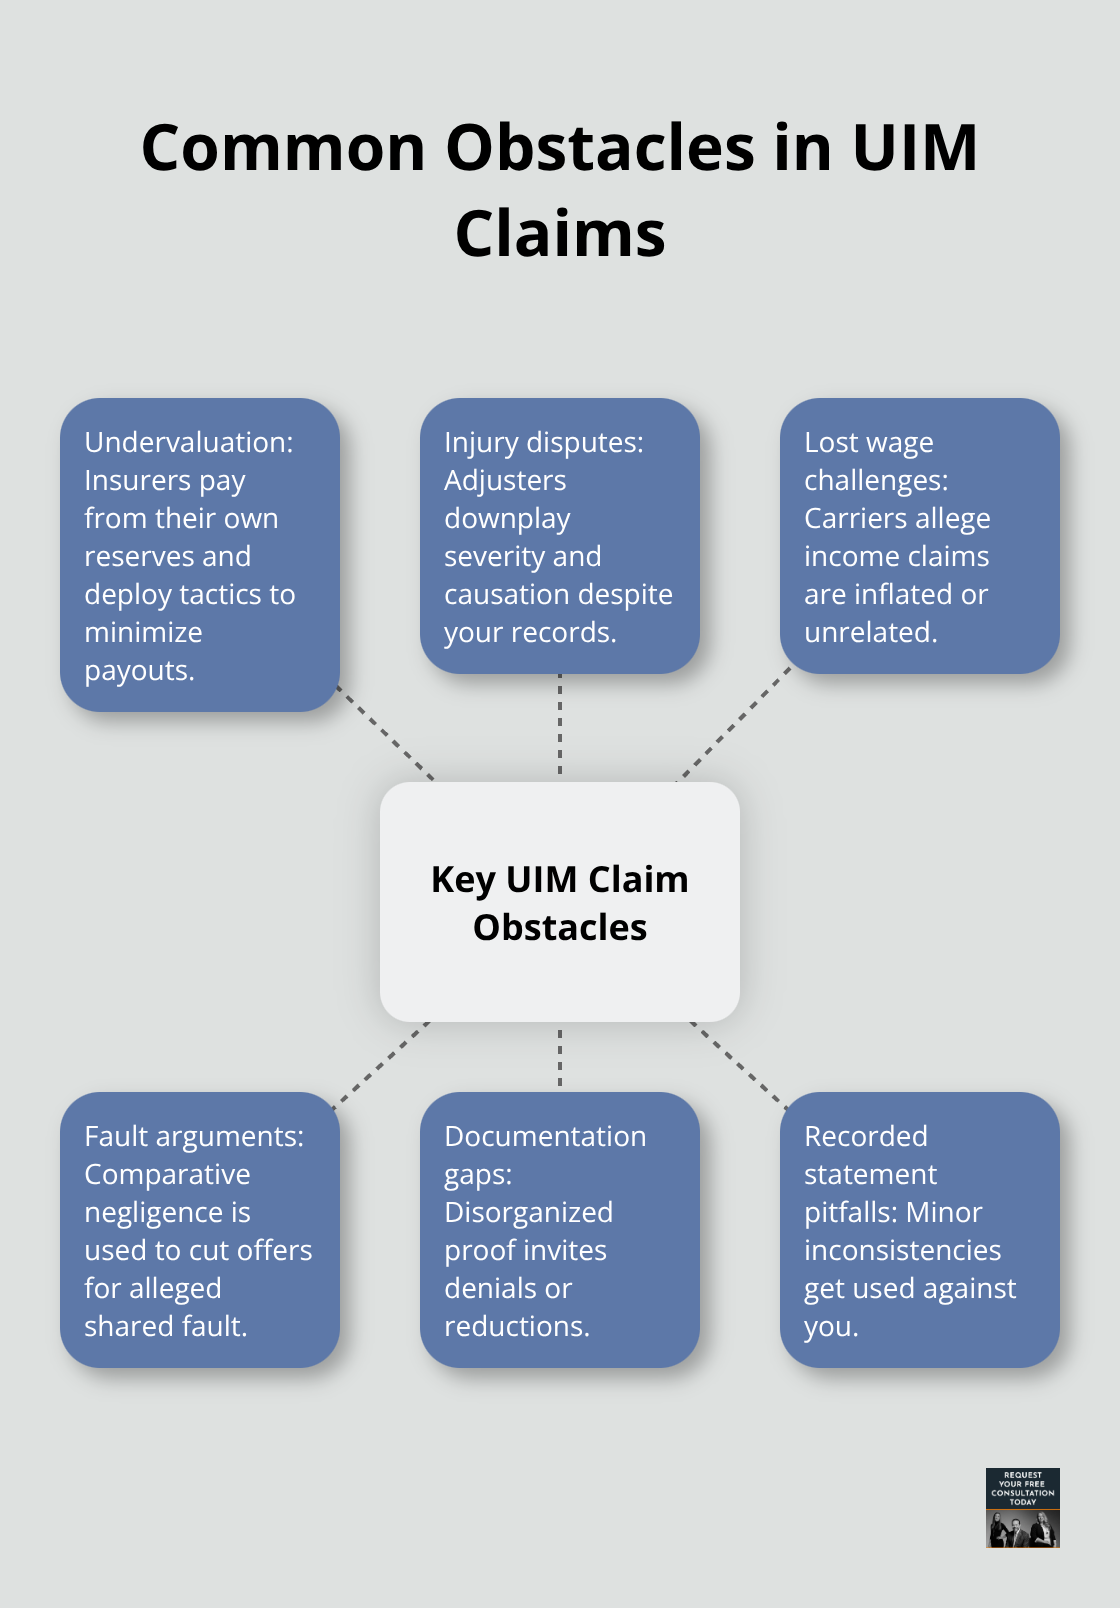
Insurance companies systematically undervalue UIM claims because they pay from their own reserves rather than a third party’s policy. When you file a UIM claim, the adjuster’s primary motivation shifts from customer service to cost containment, and that shift manifests in aggressive tactics designed to minimize your recovery. Adjusters argue your injuries aren’t as severe as your medical records indicate, claim your lost wages are inflated, or dispute whether the accident caused your damages at all.
The National Association of Insurance Commissioners found that UIM claims face denial or underpayment rates exceeding 30% when claimants lack proper documentation or legal representation.
You’ll encounter arguments that your treatment was excessive, that you could have returned to work sooner, or that your pain complaints lack objective medical support. The adjuster’s recorded statement becomes weaponized against you-any hesitation in your answer or minor inconsistency gets flagged as evidence of an exaggerated claim. Insurance companies also employ comparative negligence arguments aggressively in UIM disputes, claiming you contributed to the accident and therefore deserve reduced compensation. In California, you can recover damages even if you’re partially at fault, but the insurance company will use any percentage of fault attribution to slash your settlement offer.
Disputes Over Fault and Liability
The fault determination process in UIM claims operates differently than you might expect, and insurance companies exploit this difference regularly. Your own insurance company has financial incentive to minimize your UIM payout by arguing the at-fault driver bears less responsibility than your claim documents suggest. If the at-fault driver’s insurance company disputes liability, your insurance company won’t automatically side with you-they conduct their own investigation and may conclude the accident involved shared fault. This creates a situation where you fight two insurance companies simultaneously, each trying to reduce their financial exposure.
Sacramento and Oakland accident victims frequently encounter disputes when multiple vehicles are involved or when liability isn’t immediately obvious from police reports. The adjuster will request independent medical examinations from doctors selected by the insurance company (these physicians typically produce findings minimizing your injuries, and their reports carry substantial weight in settlement negotiations). Countering these tactics requires organizing your medical evidence to show clear causation between the accident and your injuries, maintaining consistent documentation throughout your recovery, and refusing to accept the insurance company’s initial lowball offers. Insurance companies count on people accepting inadequate settlements out of frustration or financial pressure, so standing firm on your claim’s actual value becomes essential to your recovery.
Navigating Multiple Insurance Policies
When multiple insurance policies intersect-your UIM coverage, the at-fault driver’s liability policy, and potentially uninsured/underinsured coverage from additional household vehicles-the coordination between these policies becomes a minefield. Some policies contain anti-stacking provisions that prevent you from combining coverage limits across vehicles, though California law limits how restrictive these provisions can be. Your insurance company will argue that your damages shouldn’t exceed what the at-fault driver’s policy would have covered if they carried adequate limits, a position that directly contradicts the purpose of UIM protection.
If you carry multiple policies or if your household members carry policies that could apply, coordination of benefits disputes arise frequently, with each insurance company claiming another should pay first. The practical solution involves obtaining copies of all potentially applicable policies before filing your claim and understanding their specific language around stacking, coordination, and priority. Document every communication with every insurance company involved, including dates, times, and what each representative told you about how your claim would be handled. When navigating these disputes, experienced legal guidance becomes invaluable-we at Schaar & Silva LLP assist clients throughout Santa Cruz County, Sacramento, and Oakland in coordinating complex multi-policy claims and countering insurance company tactics designed to minimize your recovery.
Final Thoughts
Your underinsured motorist claim represents your path to full financial recovery after an accident that wasn’t your fault. The obstacles we’ve outlined-insurance company undervaluation, liability disputes, and multi-policy coordination-are real challenges, but they’re not insurmountable. Accident victims who document their injuries thoroughly, communicate promptly with their insurance company, and organize their evidence systematically recover substantially more than those who navigate the process alone.
The financial stakes are significant. Santa Cruz County, Sacramento, and Oakland accident victims frequently face gaps of $50,000 to $200,000 or more between the at-fault driver’s coverage and their actual damages. That gap represents your medical expenses, lost wages, and the genuine suffering you’ve endured. Your insurance company’s initial settlement offer will almost certainly fall short of what your underinsured motorist claim actually warrants-this is standard practice, not a reflection of your claim’s weakness.
Consider legal guidance when your injuries are serious, when the at-fault driver’s insurance disputes liability, when your own insurance company undervalues your damages, or when multiple insurance policies complicate your claim. An attorney levels the playing field against insurance companies that employ adjusters trained specifically to minimize payouts. We at Schaar & Silva LLP help accident victims throughout Santa Cruz County navigate underinsured motorist claims with medical bill assistance, property damage evaluation, and connection to support specialists-you can learn more about how we assist clients at schaarsilvalaw.com.