
An accident with an uninsured driver can leave you scrambling for answers. You’re injured, your vehicle is damaged, and the other driver has no insurance to cover the costs.
At Schaar & Silva LLP, we help accident victims in Santa Cruz County understand how uninsured motorist California coverage works and what it means for your claim. This guide walks you through your options and the steps to recover what you’re owed.
What Uninsured Motorist Coverage Actually Covers
Understanding Uninsured Drivers in California
An uninsured motorist in California is someone who drives without active liability insurance or with coverage so minimal it fails to meet state requirements. California law mandates that drivers carry at least $15,000 in bodily injury liability per person and $30,000 per accident, plus $5,000 in property damage liability. When you collide with someone who lacks this coverage, the at-fault driver cannot legally compensate you. This is where uninsured motorist coverage becomes your financial lifeline. The Insurance Information Institute reports that roughly 13% of drivers nationwide lack any insurance, though rates vary significantly by state and region. In Santa Cruz County, uninsured and underinsured drivers create genuine financial risk for responsible motorists.
What Your Coverage Actually Pays
Your uninsured motorist coverage pays for medical bills, lost wages, and pain and suffering when the at-fault driver has no insurance or insufficient coverage. The coverage works differently than standard liability claims. With a typical accident, the other driver’s insurance pays your damages. With uninsured motorist claims, your own insurance company becomes the payer, which fundamentally changes how negotiations happen. Your insurer investigates the claim just as thoroughly as they would a liability claim, but they’re now paying from your policy rather than someone else’s. This means your adjuster has stronger incentive to scrutinize expenses and challenge medical treatment necessity.
How Claims Take Longer to Resolve
Uninsured motorist claims often take longer to resolve because your insurance company conducts more detailed reviews. Coverage limits matter significantly here. If your policy has $25,000 in uninsured motorist coverage and your damages total $50,000, you’ll only recover $25,000 unless you have underinsured motorist coverage (which applies when the at-fault driver has some insurance but it’s insufficient). Most Santa Cruz residents carry between $15,000 and $100,000 in uninsured motorist limits, depending on their financial situation and risk tolerance. You should review your current policy limits immediately after an accident to understand exactly what protection you have.
Understanding your coverage limits sets the stage for what happens next in the claims process.
How Your Coverage Protects You After an Accident
Your Coverage Activates Immediately
Your uninsured motorist coverage activates the moment you file a claim with your own insurance company rather than pursuing the at-fault driver’s policy. When the other driver has no insurance, your policy becomes your protection mechanism. Your insurance company pays your medical expenses, vehicle repairs, lost income, and pain and suffering up to your coverage limits. The National Association of Insurance Commissioners found that uninsured motorist claims resolve in an average of 6 to 12 months, though straightforward cases settle faster.
Understanding Your Coverage Limits
Your coverage limits determine your maximum recovery. If you carry $50,000 in uninsured motorist protection and your damages total $75,000, you receive $50,000. If you also have underinsured motorist coverage (which applies when the at-fault driver has minimal insurance), that kicks in for the remaining $25,000 if it’s available. Most Santa Cruz residents should carry at least $50,000 in uninsured motorist limits given the prevalence of uninsured drivers in our region. Lower limits leave you personally responsible for damages exceeding your coverage.
Gathering and Submitting Required Documentation
You must submit detailed documentation to your insurance adjuster within a specific timeframe, typically 30 days after the accident though your policy specifies exact requirements. Obtain the accident report from the California Highway Patrol or local Santa Cruz police department immediately, as this document proves the other driver lacked insurance. Collect medical records, repair estimates, and proof of lost wages from your employer. Photograph your vehicle damage and the accident scene if possible. Your adjuster will investigate whether the at-fault driver truly had no insurance and whether their negligence caused your injuries. This investigation typically takes 4 to 8 weeks.
Managing Settlement Offers and Medical Treatment
Your adjuster may offer a settlement before completing their investigation, but accepting prematurely often means leaving compensation on the table. Medical treatment should continue until your doctor releases you, as settling before full recovery prevents additional claims. Document every expense and treatment related to your accident because your adjuster will scrutinize medical necessity more carefully than in standard liability claims. Your adjuster has stronger incentive to challenge medical treatment necessity since your insurer now pays from your policy rather than someone else’s.
What Happens When Negotiations Begin
Once your adjuster completes their investigation, the negotiation phase determines your final settlement amount. Your insurer conducts more detailed reviews in uninsured motorist claims than in standard liability cases, which means the process takes longer but also means thorough documentation strengthens your position. The adjuster will request additional medical records, wage statements, and repair invoices to validate your damages. You should respond promptly to all requests and provide complete information to avoid delays. When settlement discussions begin, your documented expenses and medical records become your strongest negotiating tools.
Navigating the Claims Process
Photograph Everything at the Accident Scene
The accident scene holds evidence that will directly influence your settlement amount. Photograph your vehicle damage from multiple angles, road conditions, traffic signals, street signs, and the overall scene layout. Take close-up photos of the other driver’s license plate and vehicle identification number, which helps your adjuster verify whether the driver actually carried no insurance. If you’re injured, photograph visible injuries at the scene and continue documenting them daily for the first two weeks as bruising and swelling evolve.
File Your Police Report Quickly
Police reports filed in Santa Cruz County within 24 hours carry significantly more weight than delayed reports because memory details remain accurate. Request the accident report number from responding officers and obtain a copy within 48 hours rather than waiting weeks. This document becomes critical evidence that the at-fault driver lacked insurance coverage.
Collect Witness Information
Witness contact information matters enormously-collect names, phone numbers, and email addresses from anyone who saw the accident, as uninsured motorist claims rely heavily on independent witness accounts to corroborate your version of events. Your adjuster will contact these witnesses to verify that the at-fault driver caused the collision, which strengthens your negotiating position substantially.
Respond Quickly to Your Adjuster’s Requests
Insurance adjusters approach uninsured motorist claims with heightened scrutiny because your insurer now pays your damages instead of another driver’s insurer. Respond to every document request within five business days, not the full 30 days your policy technically allows, because delays signal weakness and invite additional questioning. Medical records require particular attention-your adjuster will cross-reference treatment dates with the accident date, so gaps in treatment lasting more than two weeks often trigger skepticism about injury severity.
Maintain a detailed expense log documenting every cost related to your accident: copays, prescription medications, transportation to medical appointments, and lost work hours. When your adjuster contacts you, stick to facts and avoid emotional language, as insurance companies train adjusters to view emotional appeals as exaggeration.
Address Common Challenges Head-On
Common obstacles include adjusters claiming medical treatment was unnecessary or that your injuries preexisted the accident. Counter these challenges with your doctor’s written statements explaining how the accident caused or aggravated your injuries. If your adjuster denies your claim or offers substantially less than your documented damages, you have the right to pursue independent medical evaluation or request the insurance company conduct their own examination.
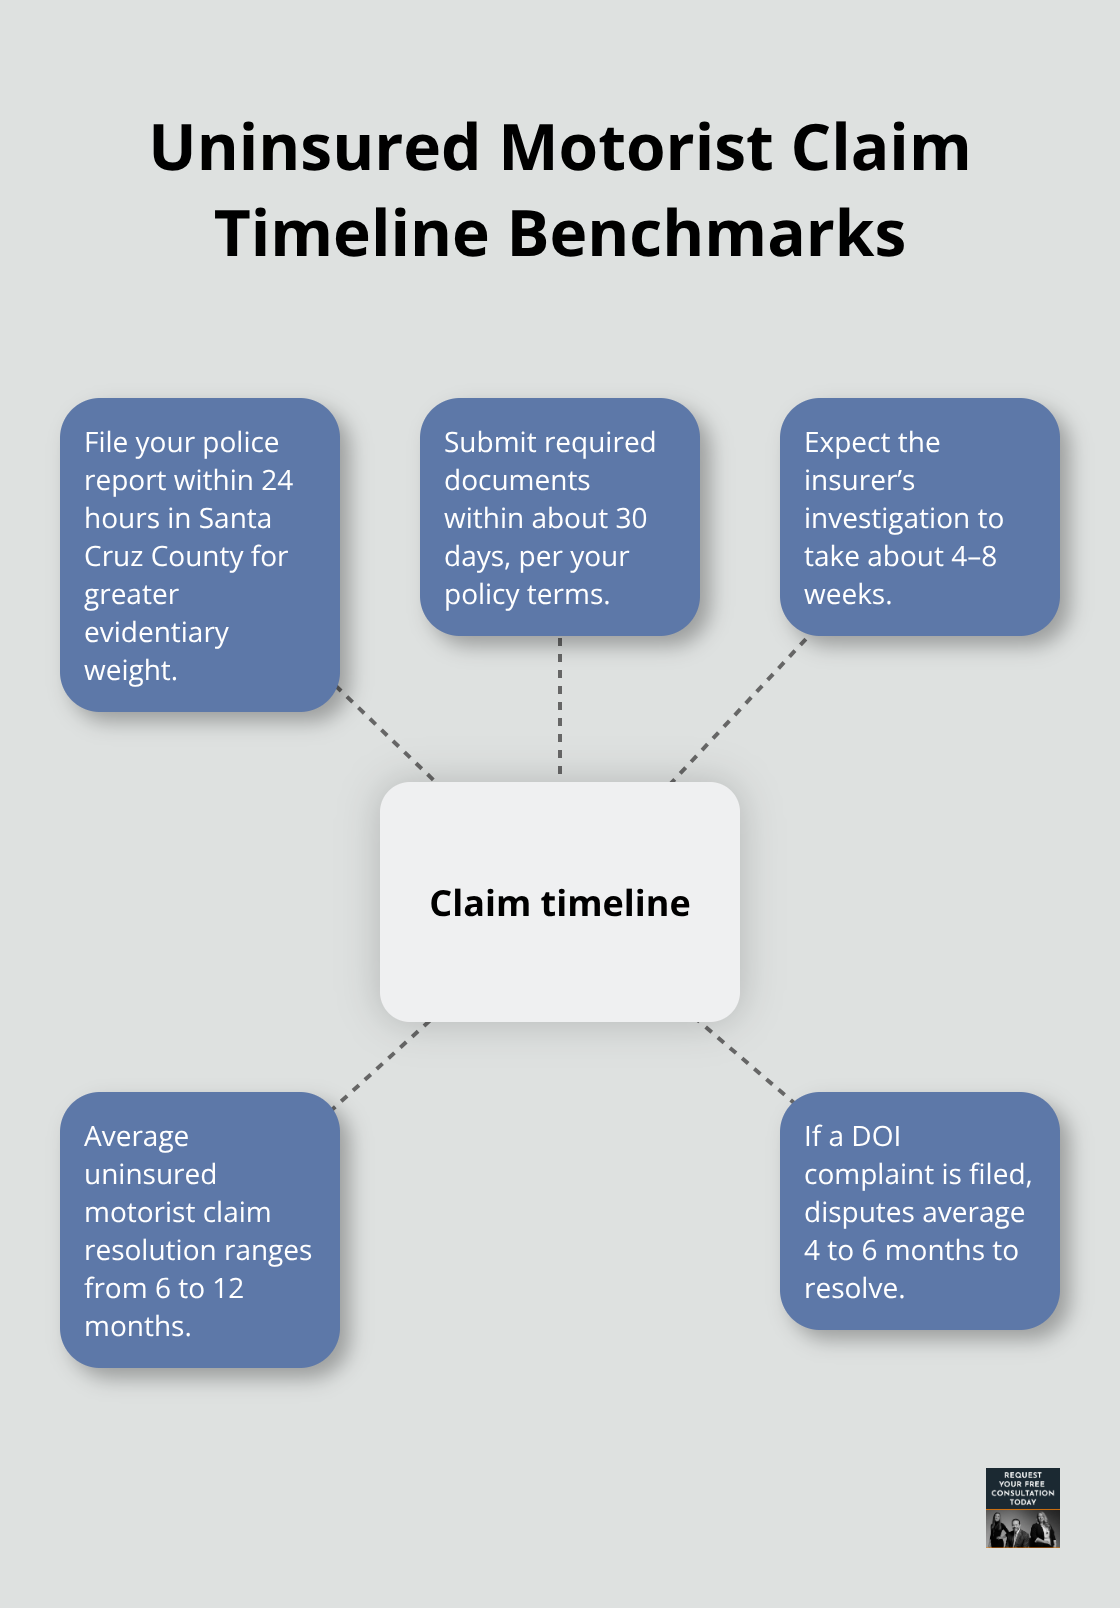
The California Department of Insurance reports that uninsured motorist disputes resolved through formal complaint processes take an average of four to six months but often result in significantly higher settlements than initial offers. At Schaar & Silva LLP, we guide Santa Cruz accident victims through this process to prevent adjusters from undervaluing legitimate claims.
Final Thoughts
Uninsured motorist California coverage protects you when the at-fault driver carries no insurance, covering your medical expenses, lost wages, and pain and suffering up to your policy limits. Without this protection, you absorb the full cost of injuries and vehicle damage yourself, which can easily reach tens of thousands of dollars. The reality is that roughly 13% of drivers nationwide operate without insurance, making this coverage essential for Santa Cruz residents.
File a police report within 24 hours, photograph all accident scene details, and contact your insurance company immediately to initiate your uninsured motorist claim. Gather witness information, collect medical records, and maintain detailed documentation of every expense related to your accident. Respond promptly to your adjuster’s requests and stick to facts rather than emotional appeals, as this approach strengthens your negotiating position significantly.
At Schaar & Silva LLP, we guide Santa Cruz accident victims through uninsured motorist claims to prevent adjusters from undervaluing legitimate damages. We assist with medical bill navigation, property damage evaluation, and connecting you with support resources when needed. Contact us to discuss your specific situation and understand your rights under California law.
